In this guide
- The key points
- Key terms, in plain words
- The routes, as cards
- Which profile, which route
- How Mauritius taxes you once you live there
- The bridge to Africa and India
- If you leave Germany for Mauritius
- If you leave Romania for Mauritius
- The Cyprus angle: if your company or your residence is in Cyprus
- Documents to prepare
- How we do it: the order of steps
- The first 90 days
- The most common mistakes
- Three illustrations
- The circle you join
- How it compares with Cyprus, and when it beats Cyprus
- FAQ
- Next steps
- Sources
Status as of 4 November 2026: based on the Immigration Act 2022 of Mauritius and the Economic Development Board guidelines on Occupation Permits and Residence Permits updated on 8 October 2026, the Premium Visa rules of the Passport and Immigration Office and the EDB, the Income Tax Act 1995 of Mauritius as summarised by PwC Mauritius (last reviewed 15 June 2026), the Mauritius Revenue Authority list of double taxation agreements, the 2024 protocol to the India Mauritius treaty, which has entered into force, the Germany Mauritius double taxation agreement of 7 October 2011, the list of Romanian tax conventions published by ANAF (updated 24 June 2026), the Romanian Fiscal Code, the German Fiscal Code (§§ 8, 9 AO) and the German Foreign Tax Act (§§ 2, 6 AStG). We will update this guide when the law or official practice changes.
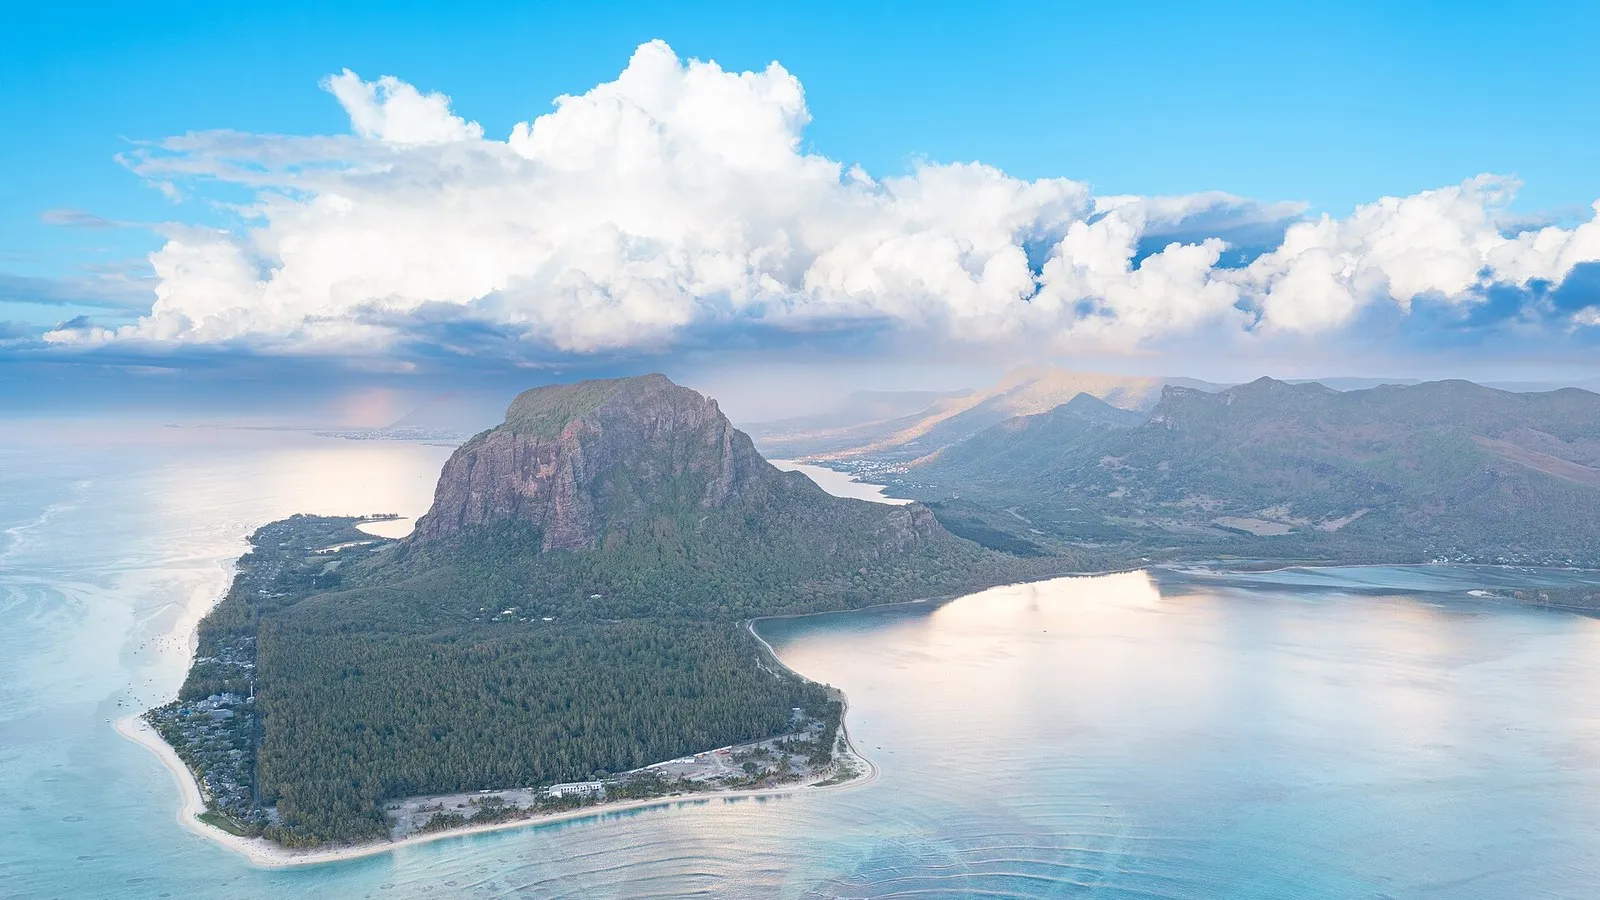
Most people think of Mauritius as a honeymoon. White sand at Le Morne, a lagoon so clear you can count the fish, a mountain that looks painted onto the sky. They come for ten days and leave with a tan.
A smaller group sees something else. An island in the Indian Ocean, four hours ahead of London in winter, the same time zone as Dubai, where English and French are both at home. A state with a 15% corporate rate, no capital gains tax and an individual tax that reaches foreign income only when it is brought into the country. A treaty network that runs to India, the United Kingdom, Germany, the United Arab Emirates and a long list of African states. And a residence permit that lasts ten years, with a path to a 20-year permanent residence.
Until now, this was the quiet base of African mining families, Indian funds and European entrepreneurs who had learned where the large money sits. They did not advertise it. Now you can use it too, with a plan that fits your situation, through ENCC. We design the route, and licensed lawyers, corporate service providers and tax advisers in Mauritius and in your home country carry it out in their own name.
This guide is part of our Plan B series: second residences that give you a door out when your home state becomes too expensive, too intrusive or too unpredictable. It shows you every route into Mauritius that the EDB published in October 2026, what each one requires, how Mauritius taxes you once you live there, what Germany and Romania still claim and, at the end, how Mauritius compares with Cyprus and when it beats it.
The key points
- Ten years, not one. The Occupation Permit for investors, professionals and self-employed people and the Residence Permit for retirees are issued for up to ten years, renewable on the published criteria.
- A clear entry ticket. Investor: USD 100,000 transferred within 60 days. Self-employed: USD 50,000. Professional: a basic salary of at least MUR 50,000 a month. Retiree aged 50 or more: USD 24,000 a year or USD 2,000 a month.
- A property route. Buying a residential property of at least USD 375,000 under the approved schemes, or an apartment in an eligible building, gives a residence permit under section 8 of the Immigration Act 2022.
- A remote work route. The Premium Visa lets you stay more than six months and up to one year, renewable, with an income of at least USD 1,500 a month per adult, if you do not work in the local labour market.
- A 20-year horizon. After five years, investors, professionals, self-employed people and retirees who meet higher thresholds can apply for a 20-year Permanent Residence Permit.
- Tax on what you bring in. A Mauritius resident individual is taxed on foreign income only to the extent it is remitted to Mauritius. Personal rates are 10% and 20% above a nil band of MUR 500,000 (per PwC Mauritius tax summary, as of November 2026), and there is no capital gains tax.
- Your home state still matters. Germany has a treaty with Mauritius, so a tie-breaker is available. Romania has none, so a Romanian who moves to Mauritius stays taxable in Romania on worldwide income in the year of departure and the following three calendar years.
Key terms, in plain words
EDB. The Economic Development Board of Mauritius, which receives and processes applications for Occupation Permits and Residence Permits through its online platform.
Occupation Permit (OP). A combined work and residence permit for investors, professionals and self-employed people.
Residence Permit (RP). A permit to live in Mauritius without the right to work, for example for retirees, property buyers and dependants.
Permanent Residence Permit (PRP). A 20-year permit for long-term holders who meet the investment, income or transfer thresholds over five years.
Premium Visa. A long-stay visa for people who live in Mauritius but earn their income from abroad.
Remittance basis. A rule under which foreign income is taxed only when it is brought into the country, not when it is earned.
Income year. In Mauritius the tax year runs from 1 July to 30 June.
The routes, as cards
The question is not whether you can live in Mauritius. It is which door fits what you already do.
Card 1: the Premium Visa, for remote income
The Premium Visa is designed for people who want to spend a long time in Mauritius while working for clients or employers abroad. It is issued for more than six months and up to one year, and can be renewed. It is the instrument for stays of more than 180 days in a calendar year when you do not hold another permit.
The conditions, as published by the EDB and the Passport and Immigration Office: you do not enter the Mauritian labour market; your main source of income and business is outside Mauritius; you show a monthly income of at least USD 1,500 per adult, plus USD 500 for each dependant under 24; you hold travel and health insurance for the stay; and you provide details of your accommodation, a return ticket and recent bank statements.
How we do it right for you: we prepare the income evidence so that it reads clearly to the officer, align the insurance with the required cover and plan the renewal before the first year ends. For many people the Premium Visa is the first year on the island, the test before a ten-year permit.
Card 2: the Investor Occupation Permit
For people who want to run their own company in Mauritius. Under the October 2026 guidelines, the investor transfers USD 100,000 or the equivalent in freely convertible currency from abroad into the company, within 60 days of the permit being issued, with evidence of the funds and a written undertaking.
The business then has to grow: a minimum turnover of MUR 5 million from the third year of registration, and for renewal a minimum annual turnover of MUR 8 million from the fifth year. The permit is issued for up to ten years, renewable on the established criteria. A second option exists for innovative start-ups registered with an accredited incubator or with a project submitted to the EDB, with progress reports and a minimum viable product by the fifth year.
How we do it right for you: the business plan is the heart of the file. We build it around a real activity, often a regional holding, a trading company or a services business that uses Mauritius as its base, and we plan the turnover milestones so that the renewal is never a surprise.
Card 3: the Self-Employed Occupation Permit
For consultants, designers, developers and other service professionals who work for themselves. The criteria: an initial investment of USD 50,000, shown through a bank statement or a written undertaking to transfer it within 60 days, a business plan for a services activity, and letters of intent from at least three prospective clients, two of them local. Business income must reach at least MUR 2 million from the third year, and for renewal MUR 3 million a year from the fifth year. The holder may employ one local administrative staff member. The permit is issued for up to ten years.
How we do it right for you: we turn your existing client base into a coherent services plan and help you build the local relationships the letters of intent require, so that the income milestones follow from what you already do.
Card 4: the Professional Occupation Permit
For people employed by a company in Mauritius. The criterion is a basic monthly salary of at least MUR 50,000, with sector-specific rules for some professions. The permit fee depends on the length of the contract. For founders, this route matters when their own Mauritian company employs them in a senior role, subject to the conditions in the guidelines.
Card 5: the Retired Non-Citizen Residence Permit
For people aged 50 or more. The applicant shows a bank statement from the country of origin or residence with at least USD 24,000 available, transfers at least USD 2,000 to a local bank within 60 days of the permit, and then transfers either USD 24,000 a year or USD 2,000 a month. The permit is issued for up to ten years, renewable.
A retiree may not take up gainful employment but may invest in any business, provided he is not employed there and draws no salary or employment benefit from it. Retirees can also apply for a work permit or an Occupation Permit in specific sectors.
How we do it right for you: we align your pension and investment income with the transfer rhythm, so that the money that reaches Mauritius is the money you choose to spend there. That matters for tax, as you will see below.
Card 6: residence through property
Under section 8 of the Immigration Act 2022, a non-citizen who buys a residential property under the approved schemes (the Integrated Resort Scheme, the Real Estate Scheme, the Invest Hotel Scheme, the Property Development Scheme or the Smart City Scheme), or an apartment in a building of at least two floors above ground floor, for at least USD 375,000 or its equivalent, is eligible for a residence permit and is exempt from the requirement of a work or occupation permit. The spouse and dependants are covered under the conditions of the law.
How we do it right for you: we check that the project is approved under the right scheme, that the price clears the threshold in the currency of the deed and that the residence permit follows from the purchase. The developer's lawyer works for the developer. Yours works for you.
Card 7: the 20-year Permanent Residence Permit
After at least five years, long-term holders can apply for a 20-year PRP under section 13 of the Immigration Act 2022, if they meet these thresholds:
- Investor. Annual turnover of at least MUR 15 million in each of the five years before the application, or aggregate turnover of MUR 75 million over five consecutive years.
- Professional. Basic monthly salary of at least MUR 400,000 for five consecutive years, with the application filed within six months.
- Self-employed. Annual business income of at least MUR 3 million, or aggregate income of MUR 15 million over five consecutive years.
- Retiree. Transfers to Mauritius aggregating at least USD 200,000 over five years.
The PRP is the long answer. Twenty years of residence security in a stable democracy, without the yearly anxiety of renewals.
Dependants and fees
Spouses and dependent children receive residence permits as dependants. As of October 2026, the EDB lists a non-refundable application fee of USD 50, a permit fee of USD 1,000 for a ten-year Investor, Self-Employed or Retired permit, a fee of USD 400 to USD 1,000 for a Professional permit depending on the contract length, and USD 400 for each dependant's permit. Professional fees of lawyers and service providers are separate and depend on your case.
A ten-year door in the Indian Ocean. Until now, only those who knew where to look used it.
Tell us what you do, where your income comes from and who moves with you. We tell you which Mauritius route fits, what it requires and how it fits the rest of your plan.
I want my Plan B → Or start with the Plan B form
We coordinate; legal, banking and tax services are provided by independent licensed partners in their own name and under their own responsibility. This guide is general information, not tax or legal advice.
Which profile, which route
- You earn from clients abroad and want to test island life. Start with the Premium Visa. Move to the Self-Employed or Investor permit once you know you want to stay.
- You run a services business and want a company on the island. Self-Employed OP if you work alone, Investor OP if you build a team.
- You build a regional business for Africa or India. Investor OP with a Mauritian company, planned around the treaty network and substance rules.
- You are 50 or older and live from pensions and investments. Retired Non-Citizen RP.
- You want a family home and residence in one step. Property of at least USD 375,000 under an approved scheme.
- You plan for decades, not years. Any of the above, with the PRP thresholds in view from the first year.
How Mauritius taxes you once you live there
The core idea: Mauritius taxes what you earn on the island and what you bring to it, not everything you own in the world.
When you become resident
Under the Income Tax Act, an individual is resident in Mauritius for an income year if he is present for 183 days or more in that income year, or for 270 days or more in aggregate over that income year and the two preceding income years, or if he is domiciled in Mauritius unless his permanent place of abode is outside Mauritius.
Foreign income on a remittance basis
A resident individual is taxed on Mauritius source income and on foreign source income to the extent it is remitted to Mauritius. Income kept abroad is not taxed in Mauritius. This is the single most important planning point for anyone who moves with assets or income abroad.
How we do it right for you: we separate your accounts by purpose. Capital and income that stays invested abroad, and the money you transfer to live on the island. For retirees, the required transfers become part of the plan instead of a surprise.
Personal rates
According to the PwC Mauritius tax summary, as of November 2026, from the income year starting 1 July 2025 the first MUR 500,000 of chargeable income falls in a nil band, the next MUR 500,000 is taxed at 10% and the remainder at 20%. A Fair Share Contribution of 15% applies to an individual's leviable income above MUR 12 million, for the income year starting 1 July 2025 and the two following income years. There is no capital gains tax in Mauritius.
Your company
Mauritius companies pay income tax at 15%. Certain foreign source income, including foreign dividends and interest, can benefit from an 80% partial exemption, subject to substance conditions, which brings the effective rate on that income to about 3%; where the partial exemption is claimed, no foreign tax credit is available on the same income. Global Business Licence companies are taxed at 15% under the same framework. Per the same PwC Mauritius tax summary, as of November 2026, a corporate Fair Share Contribution of 5% applies to companies, other than GBL companies, with chargeable income above MUR 24 million, for income years from 1 July 2025 to 30 June 2028. Large multinational groups are subject to the domestic minimum top-up tax introduced from 1 July 2025.
The bridge to Africa and India
Mauritius is not only a beach. For decades it has been the bridge between capital and the markets of Africa and India.
Mauritius has a broad treaty network, including with India and most of Africa; check the current list with the MRA.
India. The 2024 protocol to the India Mauritius treaty, which has entered into force, adds a principal purpose test and a new preamble stating that the treaty is not meant to create opportunities for non-taxation or reduced taxation through tax evasion or avoidance. Since the 2016 Protocol, India taxes gains on Indian shares acquired by Mauritius residents from 1 April 2017. The lesson: an Indian investment through Mauritius works today only where the Mauritian company has real commercial reasons and real substance.
Status on the international lists. Mauritius left the FATF list of jurisdictions under increased monitoring in October 2021 and was removed from the EU list of high-risk third countries in 2022. It is not on Annex I of the EU list of non-cooperative jurisdictions as of 9 October 2026, and it is not on the Cyprus list of low-tax jurisdictions for 2026. For your banks in Europe, that matters.
Banking. In our experience, Mauritius banks are used to international clients, multi-currency accounts and cross-border flows to Africa, India and Europe. Opening an account still requires full due diligence: source of funds, source of wealth, tax residence and, for companies, a credible business plan. We prepare that file before the first meeting, and we choose the bank for the business, not the other way round.
If you leave Germany for Mauritius
Germany lets you go. But it checks very carefully whether you have really gone.
- Home and habitual abode. Under §§ 8 and 9 AO, you remain fully taxable in Germany as long as you keep a home there at your disposal or spend more than six months there. Deregistration alone is not enough.
- The treaty. Germany and Mauritius signed a double taxation agreement on 7 October 2011, which applies from 1 January 2013. If both states consider you resident, its tie-breaker rule decides.
- Extended limited tax liability, § 2 AStG. A German citizen who was fully taxable in Germany for at least five of the last ten years, moves to a low-tax country and keeps essential economic interests in Germany can remain taxable on German income beyond the normal limited tax liability until the end of the tenth year after leaving. Because Mauritius taxes foreign income only on remittance, it can count as a low-tax country in the sense of that rule. We test that before your move.
- Exit tax, § 6 AStG. If you hold at least 1% of a company and were fully taxable in Germany for at least seven of the last twelve years, moving abroad can trigger tax on the unrealised gain on your shares, payable on application in seven annual instalments, usually against security. Our guide to German exit tax and the Cyprus year end shows how timing works.
- German income stays German. Rent from German property, German pensions and income from a German company keep their German tax treatment, under the treaty.
If you leave Romania for Mauritius
For a Romanian, Mauritius is a door with a longer corridor.
The list of Romanian tax conventions published by ANAF, updated on 24 June 2026, has no convention with Mauritius. That has a precise consequence under article 59 of the Romanian Fiscal Code. A Romanian who moves to a state with a tax treaty can end Romanian tax residence with a residence certificate from that state, under paragraph (5). A Romanian who moves to a state without a treaty stays taxable in Romania on worldwide income in the year of departure and in the following three calendar years, under paragraph (7). The departure form under article 230(7) is filed at least 30 days before leaving.
Dividends from a Romanian company remain taxed in Romania at 16% in 2026, whatever your residence. And since 2018, Mauritius exchanges financial account information with Romania under the Common Reporting Standard.
How we do it right for you: we plan the four year window openly. For some clients Mauritius is the final destination after a period of residence in a treaty state such as Cyprus; for others the window is acceptable because their income is low during the transition. Either way, we calculate it before you buy the ticket. Our guide on the 60-day rule shows the treaty state alternative.
The Cyprus angle: if your company or your residence is in Cyprus
- Treaty. Cyprus and Mauritius have a double taxation agreement in force; check the current status with the MRA.
- Not on the lists. Mauritius is not on the Cyprus low-tax list for 2026 and not on Annex I of the EU list, so the 5% and 17% Cyprus withholding on dividends to associated companies and the non-deductibility of royalties and interest to associated companies do not apply because of Mauritius.
- Combined structures. A Cyprus holding with a Mauritian subsidiary for Africa or India, or a Mauritian company owned by a Cyprus Non-Dom resident, are combinations we design case by case, always with real management where each company says it is.
Documents to prepare
- Valid passport, with at least six months of validity, and recent photographs.
- Birth and marriage certificates, apostilled and translated where needed, for dependants.
- Bank statements showing the required funds, and evidence of the source of funds.
- Business plan for the Investor and Self-Employed routes, letters of intent for the Self-Employed route.
- Employment contract for the Professional route.
- Proof of pension or investment income for the Retired route.
- Health and travel insurance for the Premium Visa.
- Police clearance and medical documents as requested.
- For property, the reservation agreement and the scheme approval of the project.
How we do it: the order of steps
- The diagnosis. Your income, your assets, your family, your current tax residence and what you want from Mauritius.
- The home side first. German exit tax and § 2 AStG test, or the Romanian four year window, settled before the move.
- The route. Premium Visa, OP, RP or property, chosen for your profile, with the PRP thresholds in view.
- The file. Business plan, income evidence, letters of intent, apostilles and translations, prepared to the EDB checklist.
- The application. Filed by licensed partners through the EDB platform.
- Arrival and banking. Funds transferred within 60 days where required, accounts opened with full documentation.
- The tax setup. Mauritian tax registration, separation of remitted and non-remitted income, company tax registration.
- The yearly rhythm. Turnover and income milestones, transfers for retirees, renewals and the five year PRP plan.
The first 90 days
- Weeks 1 to 2. Transfer of the investment or the first retirement transfer, opening of local accounts.
- Weeks 3 to 6. Company registration, tax registration, first local contracts.
- Weeks 7 to 12. Housing, schools, health insurance and the calendar of milestones for year three.
The most common mistakes
- Treating the Premium Visa as a residence permit. It is a long-stay visa for remote income, not a ten-year permit and not a path to the PRP.
- Bringing everything onto the island. Under the remittance basis, money you remit is taxable as income where it is income. Separate capital from income before you move.
- Forgetting the turnover milestones. The Investor and Self-Employed permits require turnover or income from year three, and higher figures for renewal.
- A Romanian moving without counting the four years. No treaty means worldwide taxation in Romania for the year of departure and three more.
- A German who keeps the flat in Munich. Under § 8 AO a home at your disposal keeps you fully taxable.
- Using an Indian structure built before 2017. The 2016 and 2024 protocols changed the rules. Old structures need a review.
- Buying property below the threshold or outside an approved scheme. No residence permit follows from it.
Three illustrations
The following illustrations are composites to show how the rules work. They are not real clients.
The British consultant who started with a Premium Visa
James advises fintech companies in London and Nairobi. He spent a year in Mauritius on a Premium Visa, kept his clients abroad and his savings invested in London. When he decided to stay, he applied for a Self-Employed Occupation Permit, with letters of intent from two Mauritian firms and one Kenyan client. His foreign investment income stays abroad, and he remits what he needs to live.
The Dutch couple who retired to the west coast
Pieter and Anneke, both over 60, live from Dutch pensions and an investment portfolio. They obtained Retired Non-Citizen Residence Permits, transfer USD 2,000 a month each and keep the portfolio abroad. After five years, their transfers will exceed USD 200,000 in aggregate, and they plan to apply for the 20-year PRP.
The South African family who bought on the coast
Thabo and Lerato run a logistics business in Johannesburg and wanted a secure base with good schools. They bought a villa under the Property Development Scheme for more than USD 375,000. The residence permit covers the family. Thabo's company opened a Mauritian subsidiary with real staff for its regional business, planned under the South Africa Mauritius treaty with their South African advisers.
The circle you join
The people who choose Mauritius are not tourists who stayed. They are African industrialists, Indian investors, European entrepreneurs and retirees who did the arithmetic. They want English law traditions and a French way of life, a stable democracy and a state that does not chase their income around the world. They run companies, advise boards, sail at weekends and fly to Johannesburg, Mumbai or Paris in a few hours.
ENCC coordinates your route, from the first diagnosis to the PRP. Licensed lawyers, corporate service providers and tax advisers in Mauritius and in your home country do the legal work in their own name. You get one plan, one point of contact and a team that knows both ends of the journey.
How it compares with Cyprus, and when it beats Cyprus
Both islands are serious. They solve different problems.
Where Cyprus is stronger.
- EU membership. Cyprus is in the EU, with EU rules, EU market access and the EU freedom of movement for EU citizens. Mauritius is not.
- The 60-day rule. Cyprus offers tax residence with as little as 60 days a year on the island, under conditions, while Mauritius, like most states, uses 183 days in the income year or 270 days over three years. For people who travel, Cyprus is far more flexible.
- Non-Dom. A Cyprus Non-Dom pays 0% SDC on dividends and interest within the conditions of the law for up to 17 years, with GESY at 2.65% within the cap, whether or not the money is brought to Cyprus. See our guide on Cyprus Non-Dom.
- Romania. Cyprus has a treaty with Romania, Mauritius does not. For a Romanian, that alone can decide.
- Distance. Cyprus is a short flight from most European capitals.
When Mauritius beats Cyprus.
- You keep most of your income and capital abroad. The remittance basis taxes only what you bring in, and there is no capital gains tax.
- Your business looks to Africa or India. The treaty network, the time zone and the financial sector make Mauritius the natural base.
- You want a long, simple residence for retirement. Ten years renewable, and a 20-year PRP after five years of transfers.
- You want residence tied to a property for the family. The USD 375,000 property route is direct.
- You want distance from Europe. Some families want their Plan B outside the EU entirely.
Many of our clients do not choose one. They combine them: Cyprus as the EU base and tax residence, Mauritius as the gateway to Africa and India or the retirement home for later. We design the order.
FAQ
How long is a Mauritius residence permit valid?
Occupation Permits for investors, professionals and self-employed people and Residence Permits for retirees are issued for up to ten years, renewable on the published criteria. The Permanent Residence Permit is valid for 20 years.
How much do I have to invest for the Investor Occupation Permit?
USD 100,000 or the equivalent, transferred into the company within 60 days of the permit, followed by a turnover of at least MUR 5 million from the third year and MUR 8 million a year from the fifth year for renewal.
What does the Premium Visa require?
An income of at least USD 1,500 a month per adult and USD 500 per dependant, income from outside Mauritius, no work in the local labour market, insurance, accommodation details and a return ticket. It lasts up to one year and can be renewed.
Can I get residence by buying property in Mauritius?
Yes. A residential property of at least USD 375,000 under an approved scheme, or an apartment in an eligible building, gives a residence permit under section 8 of the Immigration Act 2022.
Does Mauritius tax my foreign income?
Only to the extent it is remitted to Mauritius. Foreign income kept abroad is not taxed in Mauritius.
What are the personal tax rates in Mauritius?
According to the PwC Mauritius tax summary, as of November 2026, from 1 July 2025 the first MUR 500,000 falls in a nil band, the next MUR 500,000 is taxed at 10% and the rest at 20%, plus a Fair Share Contribution of 15% on leviable income above MUR 12 million.
Is there capital gains tax in Mauritius?
No. Mauritius does not levy capital gains tax.
Can a retiree work in Mauritius?
A retiree on a Retired Non-Citizen permit may not take up gainful employment, but may invest in a business without being employed or paid by it, and may apply for a work permit or Occupation Permit in specific sectors.
Does Romania have a tax treaty with Mauritius?
No. Under article 59(7) of the Romanian Fiscal Code, a Romanian who moves to Mauritius stays taxable in Romania on worldwide income in the year of departure and the following three calendar years.
Does Germany have a tax treaty with Mauritius?
Yes. The agreement of 7 October 2011 applies from 1 January 2013 and includes a tie-breaker rule for dual residence.
What changed for India investments through Mauritius?
The 2024 protocol, which has entered into force, added a principal purpose test. Since 2017, India taxes gains on Indian shares acquired by Mauritius residents from 1 April 2017.
Next steps
You now know every published route into Mauritius, what it costs in official fees and what it means for your taxes at home. The next step is to choose the one that fits your life, and to plan the order in which you take it.
The state counts on you never leaving. Mauritius counts on you arriving.
Until now, a ten-year base in the Indian Ocean was for those who knew where to look. Now you can have it too.
Describe your situation in writing, and we come back with a first assessment of your Mauritius route and how it fits your plan, or book a paid 20-minute call to walk through it together. We design the plan and coordinate the licensed partners who make it real.
I want my Plan B → Or book the 20-minute call
We coordinate; legal, banking and tax work is done by independent, licensed partners in their own name and under their own responsibility. This guide is general information, not tax or legal advice.
Sources
- Economic Development Board Mauritius, Occupation Permit and Residence Permit guidelines, updated 8 October 2026: https://business.edbmauritius.org/wps/wcm/connect/business/d19ef870-5d87-42af-9108-0f494ae4897a/Updated+OP+%26+YPOP+guidelines+8.10.2026.pdf?MOD=AJPERES
- Economic Development Board Mauritius, Premium Visa FAQ: https://edbmauritius.org/wp-content/uploads/2023/12/FAQs-Premium-Visa.pdf
- Passport and Immigration Office Mauritius, Premium Visa: https://passport.govmu.org/passport/?page_id=595
- Immigration Act 2022 of Mauritius, sections 8 and 13, as described in the EDB guidelines above.
- PwC Worldwide Tax Summaries, Mauritius, individual residence (last reviewed 15 June 2026): https://taxsummaries.pwc.com/mauritius/individual/residence
- PwC Worldwide Tax Summaries, Mauritius, taxes on personal income: https://taxsummaries.pwc.com/mauritius/individual/taxes-on-personal-income
- PwC Worldwide Tax Summaries, Mauritius, income determination: https://taxsummaries.pwc.com/mauritius/individual/income-determination
- PwC Worldwide Tax Summaries, Mauritius, taxes on corporate income: https://taxsummaries.pwc.com/mauritius/corporate/taxes-on-corporate-income
- Mauritius Revenue Authority, double taxation agreements: https://www.mra.mu/taxes-duties/international-taxation/double-taxation-agreements
- Bank of Mauritius, Mauritius exits the FATF list of jurisdictions under increased monitoring: https://www.bom.mu/media/media-releases/mauritius-exits-faft-list-jurisdictions-under-increased-monitoring-list
- Council of the EU, EU list of non-cooperative jurisdictions for tax purposes: https://www.consilium.europa.eu/en/policies/eu-list-of-non-cooperative-jurisdictions/
- German Federal Ministry of Finance, double taxation agreement with Mauritius: https://www.bundesfinanzministerium.de/Content/DE/Standardartikel/Themen/Steuern/Internationales_Steuerrecht/Staatenbezogene_Informationen/Laender_A_Z/Mauritius/2012-10-09-Mauritius-Abkommen-DBA.html
- German Fiscal Code, §§ 8 and 9 AO: https://www.gesetze-im-internet.de/ao_1977/
- German Foreign Tax Act, §§ 2 and 6 AStG: https://www.gesetze-im-internet.de/astg/
- ANAF, Romanian double taxation conventions (updated 24 June 2026): https://static.anaf.ro/static/10/Anaf/AsistentaContribuabili_r/Conventii/Conventii.htm
- Romanian Fiscal Code, consolidated version, ANAF: https://static.anaf.ro/static/10/Anaf/legislatie/Cod_fiscal_norme_2023.htm
Verified on 4 November 2026.
Cover photo: Le Morne peninsula, Mauritius. Photo by dronepicr, Wikimedia Commons, CC BY 2.0, cropped.