In this guide
- The key points
- Why foundations first
- Setting up a private-benefit foundation
- How a foundation is taxed in Liechtenstein
- Banking second
- The German angle: § 15 of the Foreign Tax Act
- Running the foundation year to year
- What it costs, in practice
- Decision criteria
- Common mistakes
- Implementation: how we build it with you
- Three cases
- How to do it right
- How it compares with Cyprus, and when it beats Cyprus
- FAQ
- Next steps
- Sources
Status as of 21 October 2026: based on the Liechtenstein Persons and Companies Act (PGR), Art. 552 on foundations, the guidance of the Office of Justice on deposit of the formation notice, the Liechtenstein Tax Act (SteG), in particular Art. 61, 62 and 64, the Tax Administration's pages on income tax for legal entities and on private asset structures (updated June and September 2026), the Liechtenstein deposit protection and investor compensation foundation (EAS), and, for German readers, § 15 of the German Foreign Tax Act. Rates and rules are those in force on this date.
It's a Tuesday evening in Munich or Bucharest. Another letter from the tax office lies on the table: another rule, another "contribution", another share of your life's work claimed by people who never built anything with you. You look at what you've created and ask the question every builder asks eventually: whose work is this, really?
Now picture something else. A Swiss franc account at a bank in Vaduz. A foundation with its own assets, governed by rules you wrote, holding your family's wealth beyond the reach of any government's mood swings, and still standing when you're gone. It sounds like a fairy tale. It's a real one, because it's legal. Until yesterday, this was the toy of families with family offices and lawyers in Zurich. Today you can have it too, through ENCC.
Everything you have built, the company, the portfolio, the house, a lifetime of savings, sits in your own name today. That means it also sits within reach of anyone with a claim on you: a state that rewrites the rules next year, a creditor, a falling-out with a partner, an estate process that splits a business into pieces. The state is not your partner in protecting wealth. It is your largest creditor, and the only one that gets to write its own rules.
Families who think in generations answered this long ago. They moved wealth into a structure with its own assets, governed by rules they wrote, run by those rules even when the founder is no longer there. The Liechtenstein foundation is one of the most refined tools for the job: one of the most developed foundation laws in the world, a stable constitutional monarchy with its own courts, the Swiss franc, and trustees who have worked with family wealth for decades.
Today's Liechtenstein is not the one of accounts nobody asked about. It exchanges tax information automatically and applies European anti-money-laundering rules as an EEA member. That is precisely why it is useful: it does not sell you a hiding place, it gives you a solid, lawful structure you can defend anywhere. This guide shows what a foundation actually gets you, how to set one up properly, how it is taxed in Liechtenstein, what the bank does, and when it beats a Cyprus trust.
Picture it: a Tuesday morning, coffee on a terrace in Larnaca or Lisbon, and you know the business you built already has its rules written down, a council that follows them and a bank account in Swiss francs. Your children know what they will receive and when. Nobody fights over anything at a notary. For generations this was a tool for very wealthy families with lawyers on retainer. Today an ordinary entrepreneur who worked for what he has can have one too. We coordinate everything from the first call; licensed specialists in Liechtenstein build it.
The key points
- The foundation is the prize. Art. 552 PGR gives you one of the most flexible, best-tested legal frameworks anywhere for family wealth, succession and governance. You write the rules; the foundation lives by them.
- No commercial register entry required. A private-benefit foundation does not have to be entered in the commercial register; its beneficial owners are still reported to the Liechtenstein register of beneficial owners and known to the bank. Instead, a formation notice is deposited with the Office of Justice within 30 days, confirmed in writing by a licensed Liechtenstein lawyer, trustee or other authorised professional. (Charitable foundations are registered and supervised by STIFA.)
- A known, modest tax cost. Ordinarily 12.5% income tax on taxable net income, with a CHF 1,800 annual minimum tax credited against it.
- The PVS route for passive family wealth. A foundation with no economic activity that meets Art. 64 of the Tax Act can obtain private asset structure (PVS) status: no income tax in Liechtenstein, only the CHF 1,800 minimum tax, confirmed once a year.
- A Swiss-franc bank behind it. Well-capitalised, international banks, with deposits protected up to CHF 100,000 per depositor per bank through EAS. Bring a clear source of wealth and a clear purpose and the door opens.
- German residents: plan around § 15. The German Foreign Tax Act can attribute a foreign family foundation's income to a German-resident founder or beneficiaries; the EU/EEA exception works only when its strict conditions are built in from day one.
Why foundations first
The gain first: wealth that no longer sits in your name, and so no longer sits within anyone's reach. That is what a foundation gives you before it gives you a bank account.
A Liechtenstein foundation is a legal person that owns its assets outright, dedicated by you to a purpose and to the people you choose. No shareholders to buy out, no partners to outvote you. Unlike a common law trust, the foundation itself is the owner and acts through its council. For families from civil law countries, that is often the more natural shape: a legal person you can understand, not a trust relationship you have to take on faith.
And it is made to measure. You define the purpose, the beneficiaries or the class of beneficiaries, the distribution rules, who sits on the council and whether a protector or other supervisory body watches over it. You can reserve certain rights, such as the right to amend the foundation documents, within the limits of the law. Every one of these choices shapes how strongly the foundation protects, how other countries tax it and how smoothly it runs, so we take the time to get them right with you and the specialists.
What a foundation does for you
- Succession on your terms. Assets held by the foundation do not form part of your estate in the ordinary sense, and who benefits and when is fixed in advance. Your business or portfolio stays in one piece instead of being carved up among heirs.
- Continuity. A council, with family members and independent professionals if you wish, keeps things running when you can no longer act.
- Protection. Assets validly dedicated to the foundation are no longer your personal assets. Set it up in good time, from surplus and not against existing creditors, and that separation holds.
- Giving with structure. Charitable foundations, registered and supervised by STIFA, are an established route for families who want to give systematically.
How to keep the protection solid
The foundation works for you when you let it be a real foundation. If the founder keeps full control and treats its money as his own, the separation weakens, legally and in the eyes of tax authorities, so we build in real independence from the start. And it works in daylight: Liechtenstein applies beneficial ownership rules and banks identify founders and beneficiaries as a matter of course. That is what makes the structure defensible anywhere.
Until now, only the rich had people who did this for them. Now you do: book your consultation.
Setting up a private-benefit foundation
Here's the trick: a private-benefit foundation is set up with a formation notice to the Office of Justice, not a public commercial register entry. Your family's arrangement stays your family's business. We build it with licensed trustees in Vaduz.
Here is how we get yours established. You sign a foundation deed, in writing with certified signatures, usually with by-laws setting out the details. The law requires a minimum capital at the foundation's free disposal. A council of at least two members, or a legal person, runs it; one member is typically a licensed Liechtenstein trustee or lawyer.
The foundation acquires legal personality on valid establishment. As a private-benefit foundation without a commercial business, it does not have to be entered in the commercial register, although it may be. If it is not, each council member deposits a formation notice with the Office of Justice within 30 days: name and seat, representative, purpose, date of establishment, council members, confirmation that you designated the beneficiaries and that the minimum capital is at the foundation's free disposal, among other things. A licensed lawyer, trustee or holder of an authorisation under Art. 180a PGR confirms the information in writing. Changes are notified within 30 days.
In practice the Liechtenstein trustee who will sit on your council runs the process: know-your-customer checks on you and the source of the assets, drafting, then deposit or registration. The first stage takes longest, which is why we help you prepare a clean source-of-wealth file before the trustee even asks.
This is exactly what we set up for you, in the right order. Let's start yours.
How a foundation is taxed in Liechtenstein
The gain: if it qualifies as a private asset structure, Liechtenstein taxes it at the fixed minimum tax, not on every franc it earns. Here's how it works and what it takes to qualify.
The ordinary regime
Liechtenstein taxes legal entities, foundations included, on net income at 12.5%, with a minimum income tax of CHF 1,800 a year credited against it (Art. 61 and Art. 62 of the Tax Act). A foundation that runs a business or earns ordinary taxable income sits here.
Private asset structures: the family-wealth route
Most family foundations do something narrower and simpler: they hold and manage investments. For exactly that, Art. 64 of the Tax Act offers private asset structure status. The conditions: no economic activity, no public offering or trading of its shares or units, plus the further conditions in the law. Status is granted on application to the Tax Administration. With it, the foundation pays no income tax in Liechtenstein, only the CHF 1,800 minimum. Each year, within nine months of the end of the tax year, it confirms that it met the conditions and its accounting duties. We make sure that confirmation is never missed.
Plan the other half too. PVS status covers the foundation in Liechtenstein; you and your beneficiaries are taxed where you live. A Cyprus-resident beneficiary receiving a distribution, or a German-resident founder to whom income is attributed, follows Cyprus or German rules. That is why tax advice in each home country is part of how we set it up.
Imagine it done a year from now. Take the first step today.
Banking second
Your franc account in Vaduz: this is the moment the dream gets an IBAN. The bank opens the door to a foundation with a clean file, and we build that file with you.
Then the bank. Liechtenstein has a small number of banks, several with long private-banking histories. As an EEA state it applies European banking and anti-money-laundering rules. The currency is the Swiss franc, which many families value as a diversification away from the euro, and deposits are protected up to CHF 100,000 per depositor per bank through the deposit protection and investor compensation foundation, EAS.
What these banks want is a clean file: full due diligence on founder, beneficiaries and source of wealth; automatic exchange of account information with your country of residence; and minimum relationship sizes typically above retail-bank levels. Arrive with the foundation documents and the source-of-wealth file ready and you are the client they want.
Living in Cyprus? A Liechtenstein account is also a way to hold part of the family's liquidity outside your country of residence, in another currency and another jurisdiction. That is diversification, a perfectly legitimate reason, and it sits alongside your normal Cyprus reporting.
The free people didn't wait for permission. Start with the Plan B form.
The German angle: § 15 of the Foreign Tax Act
You still live in Germany or Romania? Perfect, that's exactly when to build. Here's the home-country rule that matters and how we plan around it from day one.
If you are, or remain, resident in Germany, the rule to design around is § 15 of the German Foreign Tax Act. It attributes the assets and income of a family foundation with seat and management outside Germany to a German-resident founder, and otherwise to German-resident beneficiaries, in proportion to their share.
Subsection 6 gives an exception for foundations in EU or EEA states, Liechtenstein included. It applies only if the foundation's assets are shown to be legally and factually removed from the control of the founder and beneficiaries, and if information is exchanged between Germany and the foundation's state under the relevant mutual assistance rules. A founder who keeps the right to revoke or to direct distributions will usually struggle to meet that test, so the way to do it right is genuine independence, designed in from the first draft.
For a German resident, the foundation is a tool for succession and governance, with the German tax consequences understood and planned, not a way to move income out of German taxation. Once you have fully moved to Cyprus, the attribution may cease to apply to you as founder, while beneficiaries still in Germany can be affected. A German-licensed tax adviser reviews the structure before it is set up. Our guide to leaving a high-tax country for Cyprus covers the exit side.
Until now, only the rich had people who did this for them. Now you do: book your consultation.
Running the foundation year to year
Once it stands, it runs: your rules, applied by professionals, year after year.
A foundation is a living organisation, not a document in a drawer. Its strength comes from a council that meets, decides and keeps records, and that is the routine we set up with your trustee.
Council decisions. The council decides on investments within the investment policy, on distributions within the by-laws and on administration. Decisions are minuted, with reasons where discretion is used. A council that genuinely decides is what courts and tax authorities respect.
Accounting and confirmations. The foundation keeps accounts or an asset statement in line with the PGR. With PVS status, it confirms to the Tax Administration each year, within nine months of the year end, that it met the conditions and accounting duties. That deadline protects the status.
Changes. If anything in the formation notice changes, such as council members or the representative, a change notice goes to the Office of Justice within 30 days; the same applies when a reason for dissolution arises.
Beneficiaries. Their information rights depend on the documents and the law. Decide in advance how much the next generation will know and when, and write it down. No surprises at succession: that is the whole point.
Reporting where people live. Each founder and beneficiary reports at home. A Cyprus resident reports a distribution in Cyprus; a German resident deals with the German attribution rules. Account information is exchanged automatically with the countries where the controlling persons live.
This is exactly what we set up for you, in the right order. Let's start yours.
What it costs, in practice
What once cost a family office now costs a clear, planned budget. Here's what you pay and what you get.
We do not publish price lists for other people's services, and fees vary widely. What we do is put a written estimate for every cost category in front of you before you decide:
- Set-up: legal drafting, due diligence, the minimum capital and the deposit or registration.
- Annual governance: professional council members and the representative.
- Accounting and tax: annual accounts or asset statement, the PVS confirmation or tax return, and the CHF 1,800 minimum tax.
- Banking and investment: account, custody and asset-management fees, and the bank's minimum relationship size.
- Advice at home: the tax adviser in each country where founder and beneficiaries live.
The foundation shines for substantial family wealth with a long horizon. If you are not there yet, we start you with a Cyprus trust, a well-drafted will and good insurance, and build towards the foundation as your wealth grows.
Imagine it done a year from now. Take the first step today.
Stop financing a state that treats you as a resource. Start building the life of the free people.
Want to know whether a foundation fits your family?
In a consultation we start from what you want to protect and for whom, then coordinate with licensed specialists in Liechtenstein and in your country of residence on which structure makes sense for you.
I want my structure → Or start with the Plan B form
We coordinate; legal, trust and tax work is done by independent, licensed partners in their own name and under their own responsibility.
Decision criteria
This is where you decide, and the decision is yours, not the state's. Run through these points and you'll know in ten minutes which structure fits your life.
- Name your purpose. Succession, governance and protection are what a foundation delivers best; build around them and the tax side follows its own rules.
- Match the size. Professional council and bank relationship make the foundation ideal for substantial family wealth; for a smaller portfolio, we start with the lighter tools above.
- Decide how much independence you give it. The stronger the separation, the stronger the protection and, for German residents, the better the chance of the EU/EEA exception.
- Map where your beneficiaries live. Each home country decides how distributions are taxed, so we bring in advice in each.
- Move while the sky is clear. Set it up when there is no claim and none is foreseeable.
The free people didn't wait for permission. Start with the Plan B form.
Common mistakes
Every mistake below is a gift: someone else paid for it so you don't have to. Avoid them and your structure stands from day one.
- Choosing Liechtenstein for secrecy. Information is exchanged automatically and banks know the beneficial owners. Choose it for what it really gives you: its law.
- Holding on to full control. It weakens the foundation legally and, for German residents, almost always keeps the § 15 attribution in place.
- Treating PVS status as the whole tax picture. It covers the foundation in Liechtenstein; founders and beneficiaries are taxed where they live.
- Opening the bank account first. Structure, purpose and documents first; the bank follows.
- Skipping the cost plan. Council, accounting, bank minimums and the minimum tax recur every year, so budget them from the start.
Until now, only the rich had people who did this for them. Now you do: book your consultation.
Implementation: how we build it with you
Here's the playbook, step by step. Short, ordered, done with licensed partners. This is how the free people build it.
- Purpose and family. Who benefits, when and under which rules.
- Tax advice where people live. Cyprus, Germany or wherever founder and beneficiaries reside, before anything is signed.
- A licensed Liechtenstein trustee. Due diligence, drafting and the formation notice.
- The foundation documents. Purpose, beneficiaries, council, protector, reserved rights.
- PVS status if the foundation is purely passive, then the annual confirmation.
- The bank relationship, with documents in place and a clear source-of-wealth file.
- Regular reviews, because families and laws change.
This is exactly what we set up for you, in the right order. Let's start yours.
Three cases
Imagine yourself in one of these three stories. Real-world patterns, the right order, and what it gave each of them.
Martin and Claudia, Limassol: a family business to pass on
Martin and Claudia moved from Bavaria to Limassol three years ago. They own shares in a family business in Germany and want it to stay whole for their three children. With licensed advisers in Germany, Cyprus and Liechtenstein, they look at a Liechtenstein foundation holding the shares, with distribution rules and a council that includes an independent professional. Their German adviser works through the German-law consequences, including for the two children still living in Germany.
Elena, Nicosia: Swiss francs, step one
Elena, a Romanian entrepreneur in Nicosia, wants part of the family's liquidity in Swiss francs, outside her country of residence. Step one is simple: an account in her own name at a Liechtenstein bank, the minimum relationship size accepted, the income declared in Cyprus as required. Step two, when she wants that liquidity to serve her children after her, is a foundation or a Cyprus trust, and the bank relationship is already in place.
Peter, Munich: building towards real independence
Peter, still resident in Munich, wanted a Liechtenstein foundation but also wanted to keep the right to revoke it and decide every distribution. His adviser showed him that under § 15 the income would very likely be attributed to him and the separation would be weak. So Peter is doing it in the right order: a properly drafted will now, and a foundation with real independence when he is ready for it.
Imagine it done a year from now. Take the first step today.
How to do it right
The trick isn't avoiding the rules. It's using them in the right order. Here's how we set it up right for you.
- Build early, from surplus. Protection holds when the foundation is set up before any dispute, with money you do not need for current debts. If litigation is pending, resolve it first, then build.
- Give the structure real independence. A council with an independent professional holding a real vote is what makes the separation hold, legally and for tax.
- Size it properly. If your wealth is still modest or mostly in the operating business, start with a will and a franc account in your own name; the foundation is the next step.
- Prepare your source-of-wealth file. Contracts, statements, tax returns. It shortens the longest stage and opens the bank's door.
The free people didn't wait for permission. Start with the Plan B form.
How it compares with Cyprus, and when it beats Cyprus
Liechtenstein for the wealth, Cyprus for your life: the two can work together. Here's when each one wins.
Living in Cyprus, your natural alternative is the Cyprus international trust, and both are serious tools. The Cyprus trust is a common law trust under Cyprus law, with a Cyprus trustee, a statute substantially modernised in 2012 and the comfort of proximity: same jurisdiction, time zone and courts as you. The Liechtenstein foundation is a legal person in a civil law system, outside the EU but within the EEA, with a long tradition and the Swiss franc.
Liechtenstein wins when your family comes from a civil law country and prefers a legal person, when you want wealth held outside your country of residence for diversification, when beneficiaries live in several countries and a neutral seat helps, or when you value Liechtenstein's long experience with multi-generational foundations. The Cyprus trust wins when you live in Cyprus and want a simpler local structure, when cost matters most, or when the assets are mainly in Cyprus. Many families start with one and add the other later. See our guide to the Cyprus international trust in the year of the move and today's companion on what Cyprus does not do.
Until now, only the rich had people who did this for them. Now you do: book your consultation.
FAQ
Does a Liechtenstein foundation have to be registered?
A private-benefit foundation does not have to be entered in the commercial register, but it may be. If it is not, a formation notice is deposited with the Office of Justice within 30 days, confirmed by a licensed Liechtenstein professional. Charitable foundations are registered and supervised by STIFA.
How is a Liechtenstein foundation taxed?
Ordinarily at 12.5% on net income, with a CHF 1,800 minimum tax. A purely passive foundation with private asset structure status under Art. 64 of the Tax Act pays only the CHF 1,800 minimum tax in Liechtenstein.
Does PVS status cover the family's tax too?
It covers the foundation in Liechtenstein. Founders and beneficiaries are taxed where they live, which is why we plan with advisers in each home country.
Are Liechtenstein bank deposits protected?
Yes, up to CHF 100,000 per depositor per bank, through the deposit protection and investor compensation foundation EAS.
Can a German resident use a Liechtenstein foundation?
Yes, for succession and governance, planned around § 15 of the German Foreign Tax Act, which generally attributes the income to a German-resident founder or beneficiaries. The EU/EEA exception needs real legal and factual separation from their control and information exchange.
Liechtenstein foundation or Cyprus trust?
It depends on your family. Liechtenstein suits families who prefer a legal person, want diversification outside their country of residence or have beneficiaries in several countries. A Cyprus trust suits a Cyprus resident who wants a simpler local structure. We help you choose, or combine them.
Next steps
You've seen how it works. Now it's your move.
For the Cyprus route, read the Cyprus international trust in the year of the move; for the principles, asset protection and privacy. All our guides are on the English blog.
Stop financing a state that treats you as a resource. Start building the life of the free people.
Your wealth deserves rules you write, not rules the state writes.
Tell us what you want to protect: the family business, the portfolio, succession, a Plan B in Swiss francs. We review your options with you and connect you with licensed specialists who can build the right structure, lawfully and to your measure.
I want my structure → Or start with the Plan B form
We coordinate; legal, trust and tax work is done by independent, licensed partners in their own name and under their own responsibility.
Sources
- Liechtenstein Tax Administration, income tax for legal entities (updated 10 June 2026): https://www.llv.li/de/landesverwaltung/steuerverwaltung/steuern-juristische-personen/ertragssteuer
- Liechtenstein Tax Administration, private asset structures (PVS), Art. 64 SteG (updated September 2026): https://www.llv.li/de/landesverwaltung/steuerverwaltung/steuern-juristische-personen/pvs
- Liechtenstein Tax Administration, Newsletter 01/2024 on annual PVS confirmations: https://www.llv.li/serviceportal2/amtsstellen/steuerverwaltung/newsletter/stv_newsletter_2024_01.pdf
- Liechtenstein Office of Justice, foundation: deposit in the commercial register: https://www.llv.li/de/unternehmen/gruendung-fuehrung/handelsregister-hr-/hinterlegung-im-handelsregister/stiftung
- Office of Justice, guidance on registration of a foundation or deposit of a formation notice: https://www.llv.li/serviceportal2/amtsstellen/amt-fuer-justiz/handelsregister/wegleitungen/008_wegleitung_zur_neueintragung_einer_stiftung_bzw._hinterlegung_einer_gruendungsanzeige.pdf
- EAS, deposit protection and investor compensation foundation of Liechtenstein: https://www.eas-liechtenstein.li/
- German Foreign Tax Act, § 15: https://www.gesetze-im-internet.de/astg/__15.html
Verified on 21 October 2026.
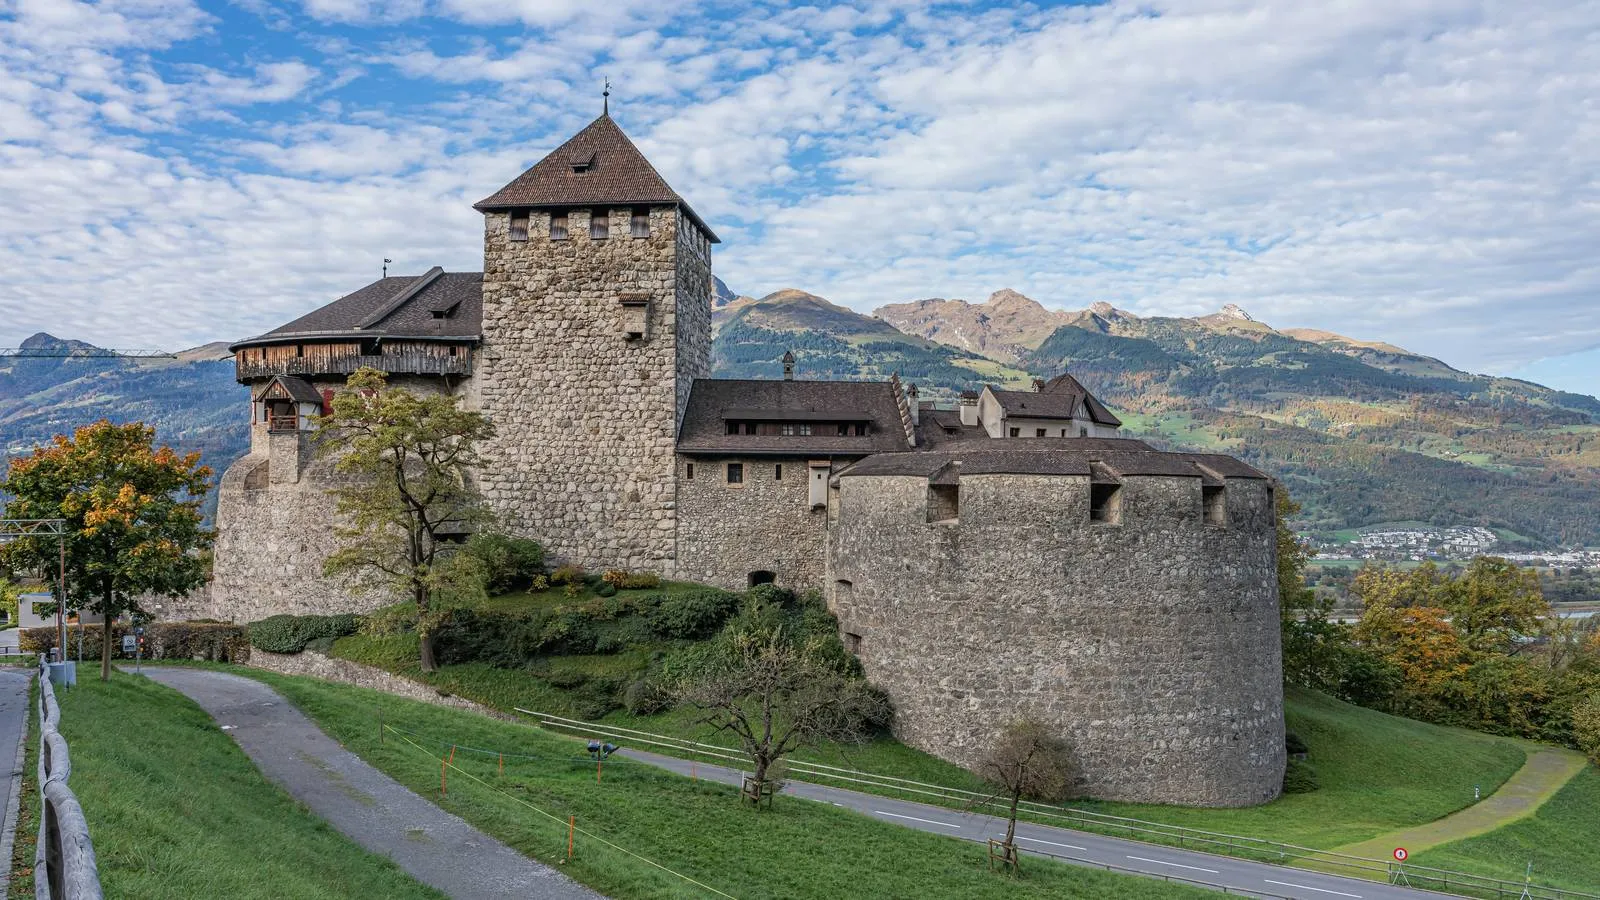
Cover photo: Vaduz Castle, Liechtenstein. Photo: A.Savin, Wikimedia Commons, Free Art License, cropped.