In this guide
- Key points
- Key terms, in plain language
- Italy: the €300,000 flat tax for new residents
- Switzerland: taxation on spending
- Greece: €100,000 plus an investment
- The United Kingdom: four years, no annual charge
- Malta and Ireland: the remittance basis survives
- Cyprus Non-Dom: the alternative without a fixed price
- How the regimes compare: the alternatives side by side
- Risks in Germany
- Risks in Romania
- Risks in Cyprus
- The sequence
- Common mistakes
- Three illustrative cases
- The circle you join
- FAQ
- Next steps
- Sources
Status as of 27 October 2026: based on Italian Presidential Decree 917/1986 (TUIR), article 24-bis, as amended by Law 199/2025 (2026 Budget Law), and the Italian Revenue Agency's guidance on the option for new residents; the Swiss Federal Act on Direct Federal Tax, article 14, and the Swiss Federal Tax Administration's figures for 2026; Greek Income Tax Code, Law 4172/2013, article 5A; the UK Finance Act 2025 rules on the foreign income and gains regime; the Cyprus Income Tax Law 118(I)/2002 and Special Defence Contribution Law 117(I)/2002 as amended for 2026, including the Tax Department's Circular 2/2026; the German Fiscal Code (§ 8 AO) and Foreign Tax Act (§ 2 and § 6 AStG); and the Romanian Fiscal Code as amended for 2026. We will update this guide when the law or official practice changes.
A lump-sum regime is a simple promise. You pay a fixed amount every year, and in return the country stops asking about most of your foreign income. For a family with large dividends, investment income or a business sale coming, the arithmetic can be compelling. For everyone else, the fixed price is often more than the tax it replaces.
In 2026 the market moved. Italy raised its flat amount for new arrivals to €300,000 a year. Switzerland's federal minimum base rose with inflation and several cantons have abolished the regime. Greece kept its €100,000 option. The United Kingdom replaced its old remittance basis with a four-year regime for new arrivals. And Cyprus, which never had a lump sum for the first seventeen years, added one for people whose Non-Dom period runs out.
This guide explains how each regime works, who it suits, what it costs in real money and how the Cyprus Non-Dom route compares. It is written for people who are deciding where to live, not for people looking for a trick.
Key points
- Italy. New residents moving from 2026 can pay €300,000 a year on all foreign income, plus €50,000 for each family member included, for up to 15 years. You must not have been Italian resident in 9 of the previous 10 years. Earlier arrivals keep €200,000 or €100,000.
- Switzerland. Foreign nationals who do not work in Switzerland can be taxed on their worldwide spending instead of income. The federal minimum base for 2026 is CHF 435,000, or seven times rent if higher, and cantons add their own minimums. Several cantons have abolished the regime.
- Greece. €100,000 a year on foreign income, plus €20,000 per relative, for up to 15 years, if you invest at least €500,000 in Greece and were not Greek resident in 7 of the previous 8 years.
- United Kingdom. From April 2025, new arrivals after ten years abroad can claim relief on foreign income and gains for their first four years of residence. There is no annual charge.
- Cyprus. No annual fee. Tax residents with Non-Dom status pay 0% Special Defence Contribution (SDC) on dividends and interest for 17 of 20 years, plus GESY of 2.65% capped at €180,000 of income. After that, from 2026, the exemption can be extended by paying €250,000 per five-year period, for up to two periods.
- The real question. A lump sum is worth it only above a certain income. Below that line, a regime without a fixed price usually costs less.
Key terms, in plain language
Lump-sum regime. A regime in which you pay a fixed annual amount, or tax on a fixed base, in place of ordinary tax on some or all foreign income.
Expenditure-based taxation. The Swiss version. Tax is calculated on your worldwide living costs, with legal minimums, instead of on your income.
Remittance basis. A regime in which foreign income is taxed only when it is brought into the country. Malta and Ireland still use versions of it for non-domiciled residents. The UK abolished it in April 2025.
Non-Dom. In Cyprus, a tax resident who is not domiciled in Cyprus under the Wills and Succession Law. Non-Dom status gives no SDC on dividends and interest.
Deemed domicile. In Cyprus, a resident who has been tax resident for 17 of the last 20 years is treated as domiciled for SDC, even if their domicile of origin is elsewhere.
Tax residence. The country that taxes you on worldwide income. Each country uses its own tests, and a lump-sum regime only works if your old country also accepts that you have left.
Italy: the €300,000 flat tax for new residents
The gain: one fixed payment covers every euro of foreign income, however large. Italy's regime under article 24-bis TUIR has become the best-known lump sum in Europe.
How it works. You transfer your tax residence to Italy and opt for the substitute tax. Every year you pay a fixed amount that covers all income produced abroad. Italian-source income, such as Italian salaries, rents or dividends from Italian companies, is taxed normally.
The amount. For people who transfer their residence to Italy from 1 January 2026, Law 199/2025 set the amount at €300,000 a year. Each family member you choose to include adds €50,000. People who moved earlier keep their amount: €200,000 for those who moved after 10 August 2024, €100,000 for earlier arrivals.
The conditions. You must not have been Italian tax resident for at least 9 of the 10 tax years before the move. The option lasts up to 15 years and can be revoked. You may exclude income from specific countries, which is then taxed normally with a foreign tax credit.
The extras. Foreign assets are outside the Italian wealth taxes on foreign property and financial assets, and gifts and inheritances of foreign assets are outside Italian inheritance and gift tax while the option is in force.
The payment. The amount is paid in one sum by the balance deadline for income tax, using code NRPP on the F24 form.
The price is high, so the regime fits only very large foreign incomes. Tell us what your income looks like and we will run the numbers.
Switzerland: taxation on spending
The gain: tax is based on how you live, not on what you earn, which suits families with very large incomes and stable spending.
How it works. Under article 14 of the Federal Act on Direct Federal Tax and the matching cantonal laws, foreign nationals who take up Swiss residence for the first time or after ten years abroad, and who do not work in Switzerland, can be taxed on their worldwide expenditure. Spouses must both meet the conditions.
The base. For direct federal tax, the base is the higher of the family's actual worldwide spending, seven times the annual rent or rental value of the home, and a federal minimum, which the Federal Tax Administration sets at CHF 435,000 for 2026. Each canton sets its own minimum for cantonal tax, often higher. The tax is then calculated on that base at ordinary rates.
The control calculation. The tax must be at least as high as ordinary tax on certain Swiss-source income and on foreign income for which you claim treaty relief.
The map. Zurich, Schaffhausen, Appenzell Ausserrhoden, Basel-Landschaft and Basel-Stadt have abolished expenditure-based taxation. It remains available in many other cantons, including Geneva, Vaud, Valais, Ticino, Bern, Zug and Schwyz.
The limit. Swiss nationals cannot use it, and you cannot work in Switzerland. Managing your own investments is generally fine; running a business from Switzerland is not.
Switzerland is a lifestyle choice with a tax framework attached. Ask us how it compares for your family.
Greece: €100,000 plus an investment
The gain: a lower fixed price than Italy, in return for a real investment in Greece.
How it works. Under article 5A of the Greek Income Tax Code, an individual who moves tax residence to Greece can pay €100,000 a year on all foreign income. Each relative included adds €20,000.
The conditions. You must not have been Greek tax resident for 7 of the 8 years before the move, and you must invest at least €500,000 in Greece, directly or through a company you control, in property, businesses, securities or similar assets, within three years.
The term. Up to 15 years. Foreign assets are also outside Greek inheritance and gift tax during the regime.
Greece is the entry-level lump sum, but the €500,000 investment is a real commitment. Let us test it against your plans.
The United Kingdom: four years, no annual charge
The gain: four clean years of foreign income and gains relief for people arriving after a long absence.
From 6 April 2025 the UK replaced the remittance basis with the foreign income and gains regime. People who become UK resident after at least ten consecutive years of non-residence can claim relief on foreign income and gains for their first four tax years of residence. There is no annual charge, but claiming the relief costs the personal allowance and capital gains annual exempt amount. After four years you are taxed on worldwide income like any other resident, and from April 2025 inheritance tax follows long-term residence rather than domicile.
Malta and Ireland: the remittance basis survives
Both countries still tax non-domiciled residents on foreign income only when it is brought into the country, with their own conditions and, in some cases, annual minimum charges. Neither is a lump-sum regime in the strict sense, and both deserve a specific review before you rely on them.
A fixed price is good value only if your income is far above it.
Want to know where your line is?
Tell us your income by type, your family and where you want to live. We compare Italy, Switzerland, Greece, the UK and Cyprus in euros, check your exit from your current country and coordinate the licensed partners who handle residence, banking and tax filings.
I want my structure → Or start with the Plan B form
We coordinate; legal, banking and tax work is done by independent licensed partners in their own name and under their own responsibility. This guide is general information, not tax or legal advice.
Cyprus Non-Dom: the alternative without a fixed price
The gain: no annual fee, and no SDC on dividends and interest from the first year, which is where most investors' income sits.
Cyprus works differently. There is no lump sum for the first seventeen years. Instead, specific income is outside the tax that would otherwise apply.
Residence. You become Cyprus tax resident either by spending more than 183 days in Cyprus in a calendar year, or under the 60-day rule: at least 60 days in Cyprus, no more than 183 days in any other single state, a business, job or office in Cyprus held in the year and not ended during it, and a permanent home there, owned or rented.
Non-Dom. If your domicile of origin is outside Cyprus, you are Non-Dom. Dividends and interest carry no SDC. GESY, the national health contribution, applies at 2.65% on income up to €180,000 a year, a maximum of €4,770.
Other income. Gains on the sale of securities are exempt from income tax. Crypto gains are taxed at a flat 8% from 2026. Salaries, pensions and business profits are taxed under the ordinary rules. Cyprus has no inheritance tax.
After seventeen years. Once you have been resident for 17 of the last 20 years, you become deemed domiciled for SDC. From 2026, if your domicile of origin is outside Cyprus, you can keep the SDC exemption by paying €250,000 per five-year period, for up to two periods. The election is irrevocable and the application is due by 30 June of the first year of the five-year period it covers, and the €250,000 is paid in one sum soon after acceptance, with no refund. At the current 5% SDC rate for domiciled residents, that payment only pays off above roughly €1 million of dividends a year.
For more, read our guides on Cyprus tax residency and Non-Dom status and on Non-Dom dividends with no SDC.
For most investors, the cheapest fixed price is none at all. Let us check whether that holds for you.
How the regimes compare: the alternatives side by side
The right regime depends on how much you earn, what kind of income it is and where you want to live. These are the comparisons we are asked for most, as of October 2026, in general terms.
Italy
Fits families with very large foreign incomes, above roughly €2 million a year, who want to live in Italy and accept a high fixed price for certainty. Italian-source income is taxed normally. The 9-of-10-year test rules out recent residents.
Switzerland
Fits wealthy foreign nationals who want Swiss life and stability, do not work in Switzerland and accept tax on a large spending base. Canton choice decides the real cost. German nationals face specific German rules after moving, covered below.
Greece
Fits investors who want an EU base with a lower fixed price and are ready to invest €500,000 in Greece. The 7-of-8-year test is lighter than Italy's.
The United Kingdom
Fits people arriving after a long absence who want four years of relief, typically to sell assets or restructure before worldwide taxation starts. It is a bridge, not a destination.
Staying where you are
Some families are better off staying put, using their home country's rules for holding companies and pensions and avoiding the cost of a move. A lump sum does not help someone whose life stays at home.
How it compares with Cyprus
Cyprus has no fixed price for seventeen years and gives Non-Doms no SDC on dividends and interest from day one, plus exempt securities gains and 8% on crypto. For a family with €300,000 of dividends, Italy's lump sum would equal 100% of that income; in Cyprus the cost is GESY of at most €4,770. Italy and Switzerland start to win only when foreign income is very large and includes types that Cyprus taxes normally, such as large foreign salaries or pensions. Greece wins when the family wants Greek life and an investment there anyway. For most entrepreneurs and investors earning through companies, Cyprus is the cheaper and simpler route.
The comparison is arithmetic, not marketing. Let us run it on your numbers.
Risks in Germany
Leaving Germany is the first test, whatever regime you choose.
- Residence. Under § 8 AO a home in Germany that you keep and are likely to use is enough for unlimited tax liability. There is no minimum number of days.
- Exit tax. § 6 AStG taxes the latent gain on shareholdings of at least 1% when you give up German residence, with payment in instalments on application.
- Extended limited tax liability. § 2 AStG can apply to German nationals moving to a country with low or preferential taxation who keep essential economic interests in Germany, for the year of departure and ten years after. A lump-sum or expenditure-based regime can count as preferential taxation.
- Inheritance and gift tax. German inheritance tax can still apply for five years after a German national leaves.
Risks in Romania
- Residence. Romania looks at domicile and the centre of vital interests. Leaving means moving both, deregistering your residence where appropriate and completing the ANAF departure formalities.
- Romanian-source income. Rents, dividends from Romanian companies and other Romanian income stay taxable in Romania under the treaty.
Risks in Cyprus
- The 60-day rule. Every condition must be met each year, including the permanent home and the Cyprus business, job or office.
- Proof. Keep a residence certificate, travel records, lease or title deeds and evidence of your Cyprus activity.
- Deemed domicile. Plan the year-17 decision early. The €250,000 election is irrevocable.
- Income types. Foreign salaries and pensions are not covered by the SDC exemption.
Every country has its trap. We check them all before you move.
The sequence
The order is the strategy.
- Income map. Every source by type and country, today and for the next five years.
- Exit test. Residence, exit tax and extended liability in your current country.
- Shortlist. Which regimes you qualify for, based on past residence and nationality.
- The numbers. Each regime's cost on your income, in euros, including the fixed price, GESY or local charges.
- Life fit. Schools, healthcare, language, travel, property.
- Residence and banking. With licensed partners, in the right order.
- The first year. Days, home, activity, filings and certificates.
- Annual review. Income, days and the long-term deadline, such as Cyprus year 17 or Italy year 15.
Common mistakes
- Choosing the regime before counting the income. A fixed price looks small next to a headline but large next to real dividends.
- Ignoring the home-country exit. Germany, Romania and the UK all have their own rules.
- Keeping the old home. A flat that stays available can keep you resident.
- Forgetting home-source income. Every regime leaves local-source income taxed normally.
- Assuming every canton offers the Swiss regime. Several have abolished it.
- Missing the Italian 9-of-10 test. Recent residents cannot use it.
- Treating the Cyprus extension as automatic. It costs €250,000 per period and only pays off at high income.
Three illustrative cases
The cases are illustrations built from typical situations, not real clients. Figures are rounded and simplified and ignore fees and personal circumstances.
A London investor weighing Italy. A 58-year-old with about €600,000 a year of dividends from a holding company is drawn to Lake Como. In Italy, the lump sum for a 2026 arrival would be €300,000, half of that income. In Cyprus as a Non-Dom, the same dividends carry no SDC, and GESY is capped at €4,770. Italy only wins if the family values Italian life above the difference.
A Dutch couple with pensions. A couple in their sixties with large occupational pensions and some investments ask about Greece. Pensions are taxed differently from dividends, and the treaty with the Netherlands may give the Netherlands the right to tax some of them. We compare the Greek €100,000 plus €20,000, with a €500,000 investment, against ordinary taxation in Cyprus and in Greece's own pensioner regime. The answer turns on the pension type.
A Dublin founder before a sale. A 42-year-old founder plans to sell a company in two years. Ireland, Italy and Switzerland all look attractive at first. In Cyprus, gains on securities are exempt and dividends from the sale proceeds carry no SDC for a Non-Dom, without a fixed price. The key risk is the Irish exit and when residence really ends, so we sequence the move well before the sale.
The circle you join
Families who use these regimes well choose a life first and a tax framework second. They count their income honestly, leave their old country properly and keep their evidence in order. When a tax authority asks, the answer is already in the file.
Cyprus gives many of them the framework without the fixed price. We help them set it up correctly and keep it that way.
Join the families who planned it properly. Start with a conversation.
FAQ
How much is the Italian flat tax for new residents in 2026?
€300,000 a year for people who move their residence to Italy from 1 January 2026, plus €50,000 for each family member included. Earlier arrivals keep €200,000 or €100,000.
Who can use the Swiss lump-sum regime?
Foreign nationals who take up Swiss residence for the first time or after ten years abroad and do not work in Switzerland. Several cantons, including Zurich, have abolished it.
What does the Greek lump-sum regime require?
€100,000 a year plus €20,000 per relative, an investment of at least €500,000 in Greece within three years, and no Greek tax residence in 7 of the previous 8 years.
Does Cyprus have a lump-sum regime?
Not for the first 17 years. Non-Dom residents pay no SDC on dividends and interest without any fixed price. After 17 of 20 years, they can extend the exemption by paying €250,000 per five-year period, for up to two periods.
Which regime is cheapest for dividend income?
For most investors, Cyprus Non-Dom, because dividends carry no SDC and GESY is capped at €4,770. Lump sums win only at very high incomes.
Is Italian income covered by the Italian flat tax?
No. Only foreign income is covered. Italian-source income is taxed under ordinary rules.
Can I keep a home in Germany while using a lump-sum regime abroad?
That is risky. Under § 8 AO, a home you keep and are likely to use can keep you tax resident in Germany, with no minimum number of days.
What happened to the UK remittance basis?
It was abolished from 6 April 2025 and replaced by a four-year foreign income and gains regime for people arriving after ten years of non-residence.
Next steps
Before choosing a regime, write down three things: your income by type and country, your family and where you would actually like to live, and when you plan any sale or restructuring. With those, we can tell you in one conversation which regimes you qualify for, what each would cost and what has to happen first. For context, read our guides on running a Cyprus company without moving and the Cyprus low-tax jurisdictions list.
The best regime is the one that fits your income and your life.
Want to compare them on your own numbers?
Tell us what you earn and where you want to live. We compare the regimes in euros, plan your exit and residence and coordinate the licensed partners who handle the move, banking and filings.
I want my structure → Or start with the Plan B form
We coordinate; legal, banking and tax work is done by independent licensed partners in their own name and under their own responsibility. This guide is general information, not tax or legal advice.
Sources
- Italian Revenue Agency, option for new residents: https://www.agenziaentrate.gov.it/portale/schede/agevolazioni/opzione-per-i-neo-residenti/infogen-opzionale-neo-residenti
- Law 199/2025, 2026 Budget Law (Normattiva): https://www.normattiva.it/eli/stato/LEGGE/2025/12/30/199/CONSOLIDATED
- Swiss Federal Tax Administration, expenditure-based taxation figures: https://www.estv.admin.ch/dam/de/sd-web/vFK3ntWLQ4s4/2-215-D-2025-d.pdf
- Swiss Federal Act on Direct Federal Tax, article 14 (Fedlex): https://www.fedlex.admin.ch/eli/cc/1991/1184_1184_1184/en
- UK HMRC, foreign income and gains regime: https://www.gov.uk/guidance/check-if-you-can-claim-the-4-year-foreign-income-and-gains-regime
- Cyprus Income Tax Law 118(I)/2002, consolidated (CyLaw, Greek): https://www.cylaw.org/nomoi/enop/non-ind/2002_1_118/full.html
- Cyprus Tax Department: https://www.gov.cy/tax/en/
- German Fiscal Code, § 8 AO: https://www.gesetze-im-internet.de/ao_1977/__8.html
- German Foreign Tax Act, § 2 AStG: https://www.gesetze-im-internet.de/astg/__2.html
- German Foreign Tax Act, § 6 AStG: https://www.gesetze-im-internet.de/astg/__6.html
Verified on 27 October 2026.
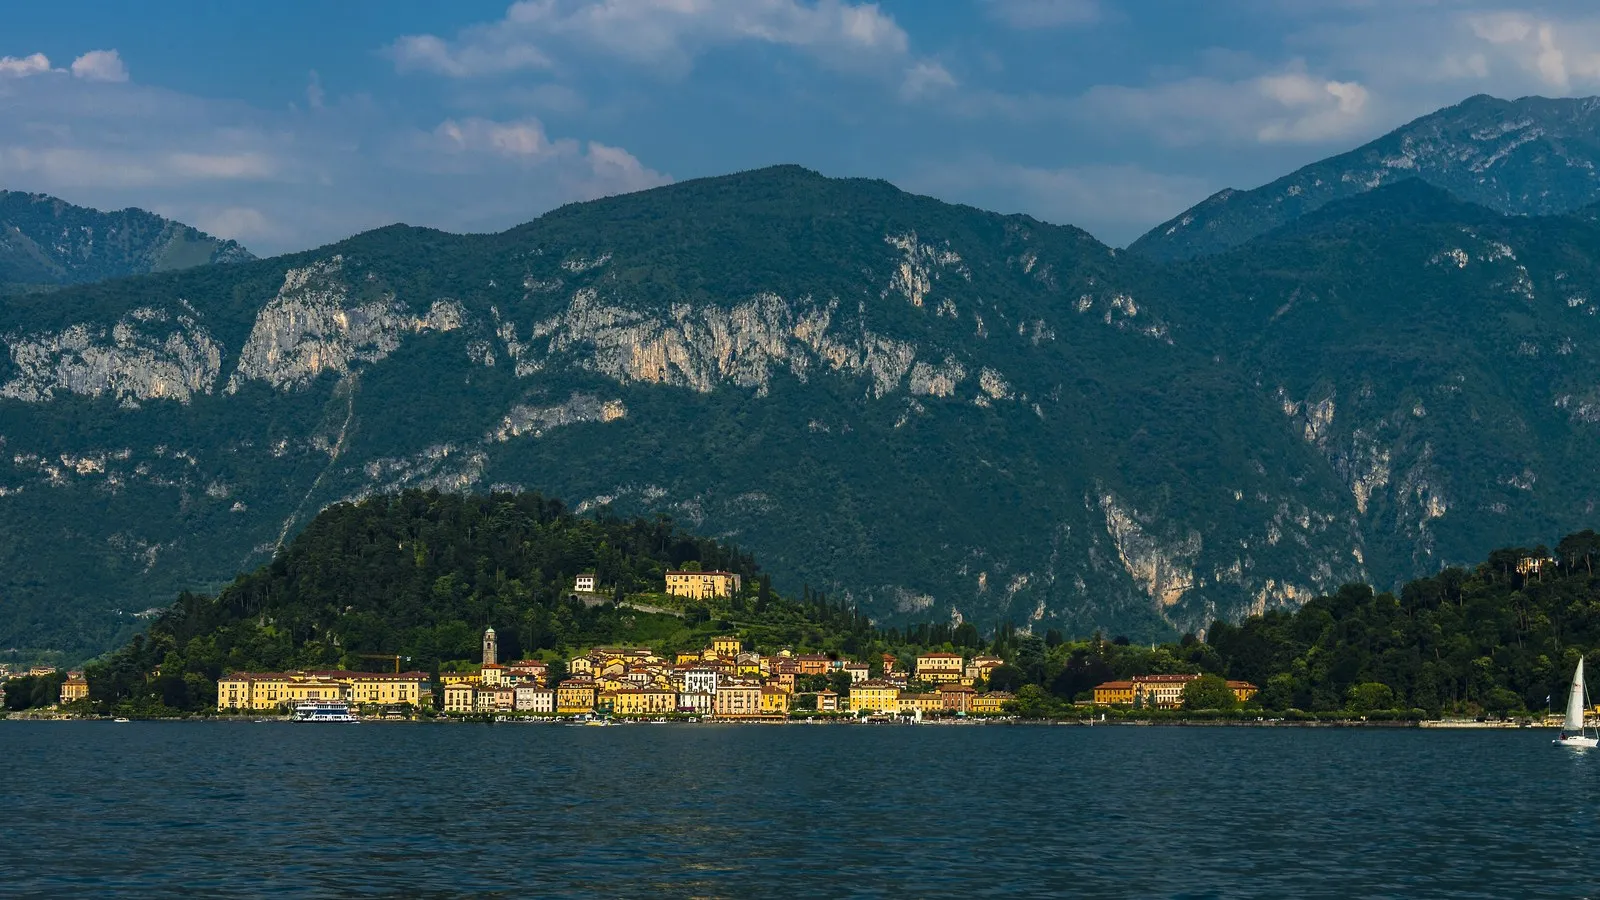
Cover photo: Bellagio on Lake Como, Italy. Photo: Daniel Case, Wikimedia Commons, CC BY-SA 3.0, cropped.