In this guide
- The key points
- Why these two cities, and why now
- Setting up in Hong Kong
- Setting up in Singapore
- How profits are taxed: two philosophies
- Banking: what Hong Kong and Singapore banks actually want
- Treaties: how each city connects to Germany, Romania and Cyprus
- If you live in Germany: what the tax office checks
- If you live in Romania: what ANAF checks
- Hong Kong, Singapore or Cyprus: how we choose
- How we do it: the order of steps
- The most common mistakes
- Three illustrations
- The circle you join
- FAQ
- Next steps
- Sources
Status as of 29 October 2026: based on the Hong Kong Companies Ordinance (Cap. 622), the Inland Revenue Ordinance (Cap. 112) including the foreign-sourced income exemption regime, the Business Registration Ordinance (Cap. 310), the Singapore Companies Act 1967, the Singapore Income Tax Act 1947 including section 10L, published guidance of the Hong Kong Companies Registry, the Hong Kong Inland Revenue Department, ACRA and IRAS, the German Fiscal Code and Foreign Tax Act, the Romanian Fiscal Code, and Article 21c of Directive 2013/36/EU. Official fees are stated as of October 2026. We update this guide when the law or official practice changes.
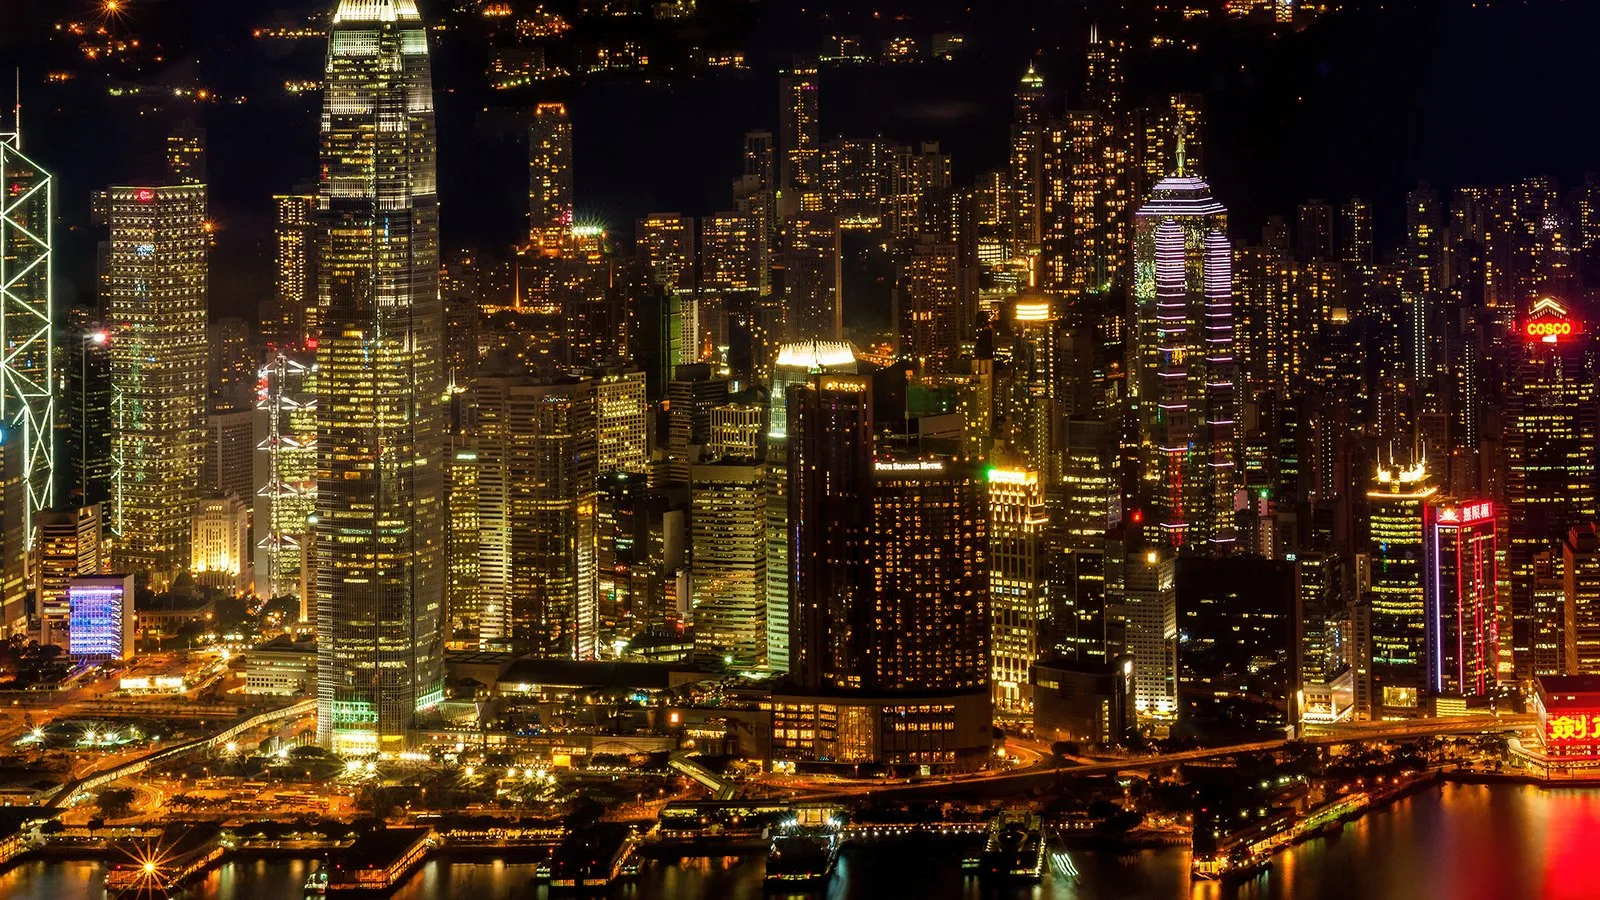
It is ten at night in Victoria Harbour and the towers of Central are still lit, floor after floor, like a ledger nobody closes. Three kilometres of water and a short flight south, Marina Bay is just as bright. Two cities that a generation ago were trading posts now hold more private capital, more shipping, more headquarters and more quiet confidence than most European capitals. And both of them did it the same way: by asking less of the people who build.
For most of the last fifty years, a company in Hong Kong or Singapore was something the rich had. A trading house in Hamburg, a family office in Geneva, a shipping dynasty. They had the lawyers who knew which city fit which business, the bankers who opened doors, and the tax advisers who made sure the structure worked back home. Everyone else read about it.
That has changed. A founder in Munich, an e-commerce seller in Bucharest, a software team in Limassol can now hold a company in either city, run it properly, bank it and keep it compliant at home. Until now only the rich could. Now you can too, with ENCC. This guide compares the two cities on what actually matters in 2026: how you form the company, who must sit on the board, how profits are taxed, how banks think, which treaties connect each city to Germany, Romania and Cyprus, and the rules your home country uses to look through a foreign company. Then we show how we choose between them, and when the honest answer is neither, but Cyprus.
The key points
- Two philosophies. Hong Kong taxes only profits sourced in Hong Kong, at 8.25% on the first HKD 2 million and 16.5% above. Singapore taxes income from Singapore and foreign income received there, at 17%, softened by partial exemptions that are generous for small companies.
- Directors. Hong Kong requires at least one natural-person director, with no residency rule, plus a company secretary resident in Hong Kong. Singapore requires at least one director ordinarily resident in Singapore.
- Setup costs are modest. Official fees, as of October 2026, run to a few thousand Hong Kong dollars in Hong Kong and a few hundred Singapore dollars in Singapore. Annual compliance, audit and the local roles are what really cost.
- Banking is about substance. Banks in both cities apply strict know-your-customer rules. A company with a real business, real counterparties and a clear story opens accounts. A shell does not.
- Your home country follows you. Germany's controlled foreign company rules, Romania's place of effective management rule and the EU's new rules for non-EU banks decide whether the structure works for an EU resident.
- Treaties differ. Romania has tax treaties with both cities. Germany has a treaty with Singapore and no comprehensive treaty with Hong Kong. Cyprus has a treaty with Singapore and signed one with Hong Kong in June 2026.
- Cyprus is often the better base for EU residents. For EU clients and EU residents, an EU company with real management is frequently the more robust tool, with Asia added later.
Why these two cities, and why now
Asia is where much of the world's growth, supply chains and new wealth sit. A presence there is not exotic any more. It is strategy.
Hong Kong is the gateway to mainland China. Its legal system is rooted in the common law, its currency is pegged to the US dollar, it has no exchange controls, and its port and airport sit at the mouth of the Pearl River Delta, the densest manufacturing region on earth. If you source products from China, sell to Chinese buyers, or trade across Asia in US dollars, Hong Kong speaks your language.
Singapore is the gateway to Southeast Asia, a region of more than 650 million people. It also has a common-law tradition, one of the most respected regulators in the world, a deep wealth management industry and a long list of tax treaties. If you serve clients across ASEAN, need regional credibility with institutions, or are thinking of moving your family to Asia, Singapore is the natural candidate.
Both cities share a temperament that Europeans rarely meet at home: the state sets clear rules, collects a modest share and then gets out of the way. Neither city asks you to justify your success. That alone explains why capital keeps flowing to them.
The question is not which city is better. It is which city fits your business, your clients and where you live. Tell us about yours.
Setting up in Hong Kong
Hong Kong lets you form a company in days, run it with a non-resident board and operate in any currency. We build it so that it also passes every check later.
Incorporation. A private company limited by shares is incorporated with the Companies Registry. As of October 2026, the official fee for electronic incorporation is HKD 1,545 and for a paper application HKD 1,720. The company registers for business registration at the same time.
Business registration. Every business in Hong Kong needs a business registration certificate from the Inland Revenue Department. From 1 April 2026, a one-year certificate costs HKD 2,200 plus a levy of HKD 150, so HKD 2,350 in total, and a three-year certificate costs HKD 6,170 including levies. The certificate is renewed and must be displayed at the place of business.
Directors and secretary. A Hong Kong private company needs at least one director who is a natural person. There is no nationality or residency requirement, so you can be the sole director from Munich or Bucharest. The company must also appoint a company secretary who, if an individual, ordinarily resides in Hong Kong, or, if a company, has its registered office or a place of business in Hong Kong. A sole director cannot also be the sole secretary. In practice, a licensed trust or company service provider fills this role.
Registered office and records. The company needs a registered office address in Hong Kong. It must keep a register of significant controllers, the people who ultimately own or control it, and make it available to authorities. Share registers, minutes and accounting records are kept in Hong Kong or available there.
Annual obligations. Each year the company files an annual return with the Companies Registry within 42 days after the anniversary of incorporation, with a fee of HKD 105 if on time, as of October 2026. Hong Kong companies generally must have their financial statements audited by a Hong Kong certified public accountant, every year, from the first. The Inland Revenue Department issues a profits tax return, normally due one month after issue, with extensions available through tax representatives. Records must be kept for seven years.
Hong Kong's setup is quick. Its discipline lies in the annual cycle: audit, return, renewal. We set the calendar on day one. For how we handle company formation in Europe, compare our guide to an EU company without moving.
Setting up in Singapore
Singapore is equally quick, but it wants someone on the ground. We build the local layer properly so the company stands on its own.
Incorporation. A private company limited by shares is registered with the Accounting and Corporate Regulatory Authority, ACRA, through its BizFile portal. As of October 2026, the official fees are SGD 15 for the name application and SGD 300 for registration. Foreigners cannot file directly; a registered filing agent files on their behalf, which our licensed partners arrange.
The resident director. Section 145 of the Companies Act requires every company to have at least one director who is ordinarily resident in Singapore. Directors must be natural persons of full age and capacity. If you move to Singapore on an appropriate work pass, you can fill this role yourself. If you stay in Europe, a qualified resident director is appointed through a licensed corporate service provider, with a clear written mandate. This is a real legal role with real duties, and we treat it as one.
Company secretary and office. The company must appoint a company secretary within six months of incorporation, and must have a registered office in Singapore, open to the public for at least three hours on each business day.
Controllers. Singapore companies keep a register of registrable controllers, the people with significant interest or control, and lodge it with ACRA.
Audit. Singapore exempts small companies from statutory audit. A private company qualifies if it meets at least two of three criteria for each of the two preceding financial years: revenue not over SGD 10 million, total assets not over SGD 10 million, and no more than 50 employees. If the company is part of a group, the whole group must qualify. Many young companies therefore avoid the cost of an audit in the early years, while still keeping full accounts.
Annual obligations. An annual return to ACRA, an annual general meeting or written resolutions, the corporate income tax return to IRAS, and an estimate of chargeable income within three months of the financial year end, unless exempt.
Singapore asks for a local anchor. That anchor is also what makes banks and partners take the company seriously. Ask us how we set it up for you.
How profits are taxed: two philosophies
Low rates are only half the story. The other half is which profits fall within the net at all. That is where the two cities differ most.
Hong Kong: the source principle. Hong Kong charges profits tax only on profits arising in or derived from Hong Kong from a trade, profession or business carried on there. Profits sourced outside Hong Kong are generally outside the charge, even if the money is received in Hong Kong. Where profits are sourced is a question of fact: where the contracts are negotiated and concluded, where the services are performed, where the operations that produce the profit take place. A Hong Kong company whose director and staff do all the work from Europe may end up with offshore profits in Hong Kong's eyes, but then the question of where the company is really managed moves to Europe. Keep that tension in mind; we return to it below.
Hong Kong rates. Under the two-tiered system, a corporation pays 8.25% on the first HKD 2 million of assessable profits and 16.5% on the rest. Only one entity in a group of connected entities can claim the lower tier. Hong Kong does not tax capital gains as such, outside the foreign-sourced income rules for multinational groups described below, and does not levy withholding tax on dividends. Gains from trading are taxed as profits.
Hong Kong's foreign-sourced income exemption. Since 2023, Hong Kong taxes certain foreign-sourced passive income received in Hong Kong by entities of multinational groups: interest, dividends, disposal gains and income from intellectual property. The income stays exempt if the entity meets the relevant exception: economic substance in Hong Kong (adequate employees and operating expenditure there, with outsourcing allowed within Hong Kong), the nexus approach for IP income, or the participation exemption for dividends and disposal gains, which requires at least a 5% holding for 12 months and is subject to anti-abuse rules. The regime applies to members of a multinational enterprise group; a standalone company owned by an individual is outside it. A company with a European parent or sister company is, however, usually part of such a group. We check the facts before anything is booked.
Singapore: residence with a remittance basis. A Singapore tax-resident company pays tax on income accruing in or derived from Singapore, and on foreign income received in Singapore. Foreign dividends, foreign branch profits and foreign service income received in Singapore can be exempt under section 13(8) of the Income Tax Act where the income was subject to tax abroad, the headline rate there was at least 15% in the year received, and the tax authority is satisfied that the exemption benefits the Singapore resident company. A company is tax-resident in Singapore if its control and management, typically its board decisions, are exercised there.
Singapore rates. The corporate tax rate is 17%. Every company gets partial exemption: 75% of the first SGD 10,000 of chargeable income and 50% of the next SGD 190,000 are exempt. New companies may instead claim the start-up exemption for their first three years of assessment: 75% of the first SGD 100,000 and 50% of the next SGD 100,000, subject to conditions such as having no more than 20 shareholders, at least one of them an individual holding at least 10%. Investment holding companies and property developers cannot use the start-up exemption. For the year of assessment 2026, companies also receive a corporate income tax rebate of 50%; together with a SGD 2,000 cash grant for active companies that meet a local-employee condition, the total benefit is capped at SGD 40,000. Singapore does not tax capital gains as such, outside the foreign disposal gains rule described below, and under its one-tier system dividends paid by a Singapore company are not taxed again in the hands of its shareholders. Gains from trading are taxed as income.
Singapore's section 10L. From 1 January 2024, gains from the sale of foreign assets received in Singapore by entities of a relevant group are taxed if the seller lacks adequate economic substance in Singapore. It is Singapore's answer to the same international pressure that shaped Hong Kong's regime.
Read the numbers together. For a small profitable company, Singapore's exemptions bring the effective rate in the early years well below the headline rate. Hong Kong's two-tier rate is lower at the top for modest profits and its source principle can leave foreign profits outside the net. Both cities now demand real substance before passive foreign income is left untouched.
The real comparison is not 8.25% against 17%. It is what your business looks like on paper and in reality. Let us model yours.
Two great cities. One structure that fits your business, your clients and your home.
Let us build it properly from the first signature.
Tell us what you do, where your clients are and where you live. We compare Hong Kong, Singapore and Cyprus for your case, design the structure and coordinate the licensed partners who form, staff, bank and keep it compliant.
I want my structure → Or start with the Plan B form
We coordinate; legal, banking and tax services are provided by independent licensed partners in their own name and under their own responsibility. This guide is general information, not tax or legal advice.
Banking: what Hong Kong and Singapore banks actually want
A company without a bank account is a name on a register. We prepare the file so the bank sees a business, not a question mark.
Banks in both cities answer to demanding regulators: the Hong Kong Monetary Authority and the Monetary Authority of Singapore. Both apply international anti-money-laundering standards and both expect banks to know who owns a company, where the money comes from and what the business actually does. Since the mid-2010s, account opening for foreign-owned companies has become slower and more selective in both cities, and it varies widely between banks.
What banks look for, in our experience, is consistent. A clear business model, ideally with counterparties in the region. A believable reason why the company is in that city and not somewhere else. Identity and address documents for directors and owners, often with an interview in person or by video. Evidence of the source of funds and source of wealth. Contracts, invoices or a pipeline that matches the story. A local address and, increasingly, local substance.
Both cities also host licensed digital banks and payment institutions, which can be faster for some profiles but have their own limits. Multi-currency accounts are normal in both, and neither city has exchange controls.
One more rule for EU residents. From 11 January 2027, under Article 21c of the EU's Capital Requirements Directive, banks outside the EU generally need an authorised EU branch to provide core banking services (deposits, lending, sureties and commitments) to EU residents. Contracts concluded before 11 July 2026 stay protected unless materially changed, and services the client requests on their own initiative remain possible. How this applies to a Hong Kong or Singapore company owned or managed from the EU is a fact-specific question. Our guide to CRD VI and non-EU banks from 2027 explains it in detail.
Banks open accounts for real businesses with real stories. Our job is to make sure yours is told completely and truthfully. Read our guide to how KYC really works, or ask us directly.
Treaties: how each city connects to Germany, Romania and Cyprus
Treaties decide whether income is taxed once or twice. They are the bridges between your company and your home.
Hong Kong. Hong Kong's network of comprehensive avoidance of double taxation agreements is narrower than Singapore's. Romania and Hong Kong have a treaty in force, applying from 1 January 2017. Germany has no comprehensive treaty with Hong Kong. Cyprus and Hong Kong signed a comprehensive agreement on 12 June 2026, which still needs to complete the procedures on both sides before it enters into force.
Singapore. Singapore has one of the broadest treaty networks in Asia. Romania and Singapore have a treaty in force since 2002, modified by the multilateral instrument. For Germany, there is the Germany-Singapore treaty, signed in 2004. Cyprus and Singapore have a treaty in force since 2001, also modified by the multilateral instrument.
What a treaty does for you. It allocates taxing rights, reduces withholding taxes where they exist, and contains a tie-breaker for companies that look resident in two countries. Modern treaties, as amended by the multilateral instrument, also contain a principal purpose test: treaty benefits can be denied where obtaining them was one of the principal purposes of an arrangement. A treaty protects a real structure. It does not rescue an artificial one.
The EU list. Neither city is on the EU list of non-cooperative jurisdictions for tax purposes. Hong Kong was removed from the list of jurisdictions under review in February 2024.
Treaties are bridges, and bridges carry weight only when both ends are solid. Ask us which bridges your case needs.
If you live in Germany: what the tax office checks
Germany looks through foreign companies more sharply than almost any other country. We design for that from the start.
Place of management. Under section 10 of the German Fiscal Code, a company's place of management is the centre of its top-level commercial direction. If you live in Germany and run your Hong Kong or Singapore company day to day from your home office, the tax office can argue that its place of management is in Germany. The company would then owe German corporate income tax and trade tax on its profits. Singapore's treaty contains rules for companies that appear resident in both countries; with Hong Kong there is no treaty to resolve the conflict.
Controlled foreign company rules. Under sections 7 and 8 of the German Foreign Tax Act, passive income of a foreign company controlled by German residents is added to their German income if it bears income tax of less than 15%. Both Hong Kong's two-tier rates and Singapore's exemptions can bring the actual burden below that line, especially for smaller companies. The definition of passive income is broad: services in which a German-resident shareholder participates can count, and so can many trading and licensing activities. The substance escape in section 8(2) applies only to companies in the EU or EEA, so it is not available for Hong Kong or Singapore.
Exit tax. If you hold shares in a company today and leave Germany, German exit tax under section 6 of the Foreign Tax Act may apply. Our guide to German exit tax and the year-end move shows the traps.
What this means. For a German resident, an Asian company works when it has a genuine Asian business, management and people in Asia, and active income. It rarely works as a remote-controlled box for European profits. Where you want to stay in Europe, an EU company with real management, often in Cyprus, is usually the more robust choice.
Germany checks. A well-designed structure is checked and still stands. Ask us how we prepare yours.
If you live in Romania: what ANAF checks
Romania's rules are simpler than Germany's, but the central question is the same: where is the company really run?
Place of effective management. Under the Romanian Fiscal Code, a foreign legal person whose place of effective management is in Romania is a Romanian tax resident. A Hong Kong company run from your living room in Bucharest can therefore be taxed in Romania as if it were Romanian, at 16% profit tax, with all the compliance that follows. The treaties with Hong Kong and Singapore contain rules for companies that appear resident in both states, but the safest path is real management in Asia or your own move.
Controlled foreign company rules. Romania's CFC rule in article 405 of the Fiscal Code applies to Romanian taxpayers subject to profit tax that control a foreign entity. An individual who holds the Hong Kong or Singapore company directly is not caught by that article. A Romanian SRL that holds it may be, and then the effective tax burden in Asia and the type of income matter.
Dividends. If you remain a Romanian resident and take dividends, Romania taxes them at 16% from 2026, with credit for foreign tax where a treaty or the law allows, and health contributions may apply.
Romania asks a fair question. We make sure the true answer is the one on paper. Tell us your situation.
Hong Kong, Singapore or Cyprus: how we choose
Every structure begins with three facts: where you live, where your clients are, and where the work is done. The right city follows from them.
Hong Kong fits when you trade physical goods with China or across Asia, invoice in US dollars, have suppliers or customers in the region, and can put real activity there: a secretary and office, regional staff or a local partner, decisions made in Hong Kong. It also fits founders who are moving to Asia and want a low headline rate on regional profits.
Singapore fits when your clients are in Southeast Asia, when institutional credibility matters, when you want a treaty network that reaches Europe, or when you are relocating your family to Asia. It also suits regional holding structures, provided the substance is real.
Cyprus fits when you are an EU resident or plan to become a Cyprus resident, when your clients are in Europe, and when you want an EU company with EU banking, EU treaties and EU-level VAT simplification. From 2026 Cyprus companies pay 15% corporate tax, and a Cyprus Non-Dom resident receives dividends at 0% SDC with GESY of 2.65% (capped). For European digital sales, an EU company can also use the Union One Stop Shop, as explained in our guide to Cyprus VAT and OSS for digital services. A Hong Kong or Singapore company selling digital services to EU consumers must use the non-Union scheme instead.
Combinations. Growing businesses often combine them: a Cyprus holding company with an Asian operating subsidiary that has real regional staff, for example. This is where treaties, controlled foreign company rules and substance must be planned together. Our guide to the Cyprus holding company shows the European side of such a structure.
The best structure is the one that matches your life. We build it around you, not around a brochure. Start the comparison for your case.
How we do it: the order of steps
Here is the path, step by step. Every step has a reason, and the order is the protection.
- The map. You describe your business, clients, suppliers, team and where you live. We decide whether Hong Kong, Singapore, Cyprus or a combination fits, and why.
- Home country check. We check management, controlled foreign company rules, exit tax and dividends in your country of residence, with your local adviser where needed.
- Substance plan. We define who decides, where, and who works for the company in the region. This plan drives every later step.
- Formation. Our licensed partners incorporate the company, appoint the directors and company secretary, and set up the registered office and registers.
- Bank file. We prepare a complete onboarding file: business plan, contracts or pipeline, source of funds, and the story of why the company is there.
- Tax registrations. Business registration and profits tax in Hong Kong; corporate tax, and GST where needed, in Singapore. VAT registrations in Europe where required.
- Accounting and audit. Bookkeeping from the first month, audit or exemption checked each year, and returns filed on time.
- Annual review. Every year we review the effective tax burden, substance, treaties and the law, and adjust.
Eight steps, one direction: a company in Asia that also holds firm when Europe looks at it. Begin with step one.
The most common mistakes
Each mistake below costs money or time. Each is avoided by an early decision.
- Choosing the city by headline rate. The rate matters less than whether the profits are within the net at all and how your home country reacts.
- Running the company from Europe. A Hong Kong or Singapore company managed from Germany or Romania invites the question of where it is really resident.
- Forgetting the controlled foreign company rules. Low effective tax plus passive income plus a German-resident controller is a well-known combination for the German tax office.
- Opening the company before the bank story is ready. Banks decide on the file. Prepare it before you form, not after.
- Treating the local roles as paperwork. A Singapore resident director and a Hong Kong company secretary have legal duties. They must be properly engaged and informed.
- Ignoring the audit. Hong Kong companies generally need an audit every year. Missing it creates penalties and banking problems.
- Selling to EU consumers without a VAT plan. Digital sales to EU consumers bring EU VAT obligations, whatever the company's home.
Mistakes are cheaper to prevent than to repair. That is why the order matters. Ask us before you sign.
Three illustrations
These are illustrations of how the rules apply, not real clients.
Daniel, e-commerce seller in Leipzig. Daniel sources home goods from factories in Guangdong and sells across Europe. He considers a Hong Kong company for sourcing. The analysis shows that his European sales, warehouse and decisions are all in Germany, so a Hong Kong company run from Leipzig would be exposed to German management and controlled foreign company rules. He decides to move to Cyprus, runs his European sales through a Cyprus company, and adds a Hong Kong sourcing company later, with a sourcing agent and an office in Hong Kong and decisions on purchasing made there.
Elena, consultant from Cluj moving to Singapore. Elena advises Southeast Asian manufacturers on European market entry and has signed two regional clients. She moves to Singapore on a work pass, becomes the resident director herself and forms a Singapore company. In its first three years it claims the start-up exemption. She leaves Romania properly, and Romania's place of effective management rule no longer concerns her company because it is genuinely run from Singapore.
Thomas and Ioana, software founders in Limassol. They live in Cyprus as Non-Dom residents and run a Cyprus company that sells software to European clients. A large Asian customer asks for a regional entity. They form a Singapore subsidiary with a local sales lead and a resident director, which invoices Asian clients. Dividends from Singapore to Cyprus are planned under the Cyprus and Singapore treaty, and the substance in both places is documented each year.
Three different lives, one principle: the city follows the business, not the other way round. Which of them are you? Tell us.
The circle you join
You are not the first to take this path, and you will not take it alone.
Our clients are founders, traders, consultants and investors from Germany, Romania, Austria and across Europe who have decided that what they build should serve them and their families first. Some trade with Asia every day; some are moving there; most simply want the freedom to choose the place that treats their work best.
ENCC coordinates. Licensed law firms, corporate service providers, accountants, tax advisers and auditors in Hong Kong, Singapore and Cyprus, engaged directly by you, do the regulated work in their own name. We make sure the pieces fit, the order is right, and nothing falls between the cracks.
This is the circle of people who build across borders and keep what they build. The door is open: join it.
FAQ
Is Hong Kong or Singapore cheaper to set up in 2026?
Official fees are modest in both. As of October 2026, Hong Kong charges HKD 1,545 for electronic incorporation plus HKD 2,350 for a one-year business registration certificate, and Singapore charges SGD 15 for the name and SGD 300 for registration. The real costs are the local roles, accounting and, in Hong Kong, the annual audit.
Can I be the only director of a Hong Kong company while living in Europe?
Yes. Hong Kong requires at least one director who is a natural person, with no residency rule. You also need a company secretary resident in Hong Kong, and a sole director cannot be the sole secretary. Managing the company from Europe, however, raises home-country tax questions.
Does Singapore require a local director?
Yes. At least one director must be ordinarily resident in Singapore. If you relocate on a suitable work pass, you can fill that role yourself; otherwise our licensed partners arrange a qualified resident director with a clear mandate.
How much profits tax does a small company pay?
In Hong Kong, 8.25% on the first HKD 2 million of assessable profits and 16.5% above, for one entity per connected group. In Singapore, 17%, reduced by partial or start-up exemptions, and for the year of assessment 2026 a 50% rebate capped at SGD 40,000.
Are foreign profits taxed?
Hong Kong taxes only Hong Kong-sourced profits, but certain foreign passive income received by group entities is taxed unless an exception such as economic substance applies. Singapore taxes foreign income received there, with exemptions for qualifying foreign dividends, branch profits and service income.
Which city has a tax treaty with Germany and Romania?
Romania has treaties with both. Germany has a treaty with Singapore and no comprehensive treaty with Hong Kong.
Can I run the company from Germany or Romania?
If you manage it day to day from there, the company may be treated as resident there, and German controlled foreign company rules may add its passive income to yours. The robust paths are real management in Asia or your own relocation.
Is Cyprus a better choice for EU residents?
Often, yes. A Cyprus company offers EU banking, EU treaties, the Union One Stop Shop for digital sales, and 0% SDC on dividends for Non-Dom residents. Asia can be added later through a regional subsidiary with real substance.
What does ENCC do and what do partners do?
We coordinate: the plan, the order, communication and quality control. Licensed law firms, corporate service providers, accountants, tax advisers and auditors, engaged directly by you, carry out formation, local roles, filings, audit and banking support under their own responsibility.
Next steps
Write down three things: where you live and plan to live, where your clients and suppliers are, and who will actually do the work and make the decisions. With that, one conversation is enough to know which city fits and what comes first. For background, read our guides on the place of effective management, relocating to Cyprus and a US LLC for Cyprus residents.
Asia's two great hubs, or Europe's sunniest. Chosen for your life, not for a brochure.
Until now, only the rich had advisers for this. Now you can too.
Describe your case in writing and we will come back with a first assessment, or book a paid 20-minute call with Bogdan to walk through it together. We design the structure and coordinate the licensed partners who make it real.
I want my structure → Or book the 20-minute call
We coordinate; legal, banking and tax services are provided by independent licensed partners in their own name and under their own responsibility. This guide is general information, not tax or legal advice.
Sources
- Hong Kong Companies Registry, fees: https://www.cr.gov.hk/en/services/fees.htm
- Hong Kong Inland Revenue Department, business registration fees and levy: https://www.ird.gov.hk/eng/pdf/brfee_table.pdf
- Hong Kong Inland Revenue Department, two-tiered profits tax rates: https://www.ird.gov.hk/eng/faq/2tr.htm
- Hong Kong Inland Revenue Department, foreign-sourced income exemption: https://www.ird.gov.hk/eng/tax/bus_fsie.htm
- Hong Kong Inland Revenue Department, comprehensive double taxation agreements: https://www.ird.gov.hk/eng/tax/dta_inc.htm
- Hong Kong Companies Ordinance (Cap. 622): https://www.elegislation.gov.hk/hk/cap622
- ACRA, fees for local companies: https://www.acra.gov.sg/how-to-guides/setting-up-a-local-company
- Singapore Companies Act 1967, section 145: https://sso.agc.gov.sg/Act/CoA1967
- IRAS, corporate income tax rates, rebates and exemptions: https://www.iras.gov.sg/taxes/corporate-income-tax/basics-of-corporate-income-tax/corporate-income-tax-rate-rebates-and-tax-exemption-schemes
- IRAS e-Tax Guide, gains or losses from the sale of foreign assets (section 10L): https://www.iras.gov.sg/media/docs/default-source/e-tax/tax-treatment-of-gains-or-losses-from-the-sale-of-foreign-assets.pdf
- IRAS, list of tax treaties: https://www.iras.gov.sg/taxes/international-tax/international-tax-agreements-concluded-by-singapore/list-of-dtas-limited-dtas-and-eoi-arrangements
- German Fiscal Code, section 10: https://www.gesetze-im-internet.de/ao_1977/__10.html
- German Foreign Tax Act, sections 6 and 8: https://www.gesetze-im-internet.de/astg/__8.html
- Council of the EU, EU list of non-cooperative jurisdictions: https://www.consilium.europa.eu/en/policies/eu-list-of-non-cooperative-jurisdictions/
- Directive (EU) 2024/1619 (CRD VI), EUR-Lex: https://eur-lex.europa.eu/eli/dir/2024/1619/oj
- ANAF, summary of 2026 tax changes: https://static.anaf.ro/static/10/Brasov/Brasov/modificari_fiscale_2026.pdf
- Cyprus Income Tax (Amending) (No. 4) Law 244(I)/2025 (CyLaw, Greek): https://www.cylaw.org/nomoi/arith/2025_1_244.pdf
Verified on 29 October 2026.
Cover photo: Victoria Harbour, Hong Kong. Photo: Wilfredor, Wikimedia Commons, CC0 1.0, cropped.